
In 1890, Woodrow Wilson, president of Princeton and eventually President of the United States, observed that “Princeton is noted in this wide world for three things: football, baseball, and collegiate instruction.”
The year Wilson made that statement, Princeton University went 11-1 in college football. Among those games was a 115-0 victory over the University of Virginia. Princeton’s lone loss came to Yale, which beat Princeton 32-0 in the final game of the season. That game was the start of a 37-game winning streak for Yale. Within that streak was a rematch with Princeton in 1891. Before more than 40,000 fans at the Polo Grounds in New York, Yale prevailed again 19-0. At this point it was clear that college football was a thriving business. In 1891 alone, Yale earned nearly $20,000 in revenue from its football team. In a nation where average incomes were less than $300, this was quite a bit of money.
Because college football was a business, one might expect it would be subject to the laws governing business in America. One of the most important of these is the Sherman Antitrust Act. Passed the same year Wilson was bragging about Princeton football, the Act makes it clear that conspiracies in restraint of trade are very much illegal.
Despite a law that clearly prohibits restraints of trade, the business of college sports has from the beginning engaged in a conspiracy to restrain the ability of its certain of its employees (the players) to sell their labor in a free market.
For those unfamiliar with the term, a monopsonist is a dominant buyer in a market with many sellers. College sports have thousands of athletes. Hence there are many sellers. But the NCAA is the dominant buyer in this labor market. As the NCAA states in its own advertisements and on its own website, “98% of the 550,000 NCAA student-athletes will go pro in something other than sports.”
Yes, a small number of college athletes do become professionals in leagues like the WNBA, NBA, and the NFL. But the NCAA admits that for 539,000 college athletes (98 percent of 550,000), the NCAA is the only employer they will ever work for in sports.
The NCAA has argued consistently in court cases that it is not a monopsonist and it is not violating the Sherman Act. At the same time, the NCAA has lobbied Congress to give it immunity to the antitrust laws, so that schools can coordinate on pay to college athletes. The NCAA argues such coordination is necessary because college sports are, in the words of Senator Ted Cruz, in “chaos,” and something has to be done to save college sports. Recently, 76 Senators in addition to Senator Cruz fell for this story by passing the Protect College Sports Act. The reality of college sports is quite different, however, from the stories the NCAA has been telling Congress and the media.
Here are six economic facts that reveal just how badly 77 U.S. Senators were fooled by NCAA lobbyists.
1. The NCAA is a monopsonist that has consistently exploited its workers for more than a century
Economic exploitation exists when a worker is paid a wage that is less than the revenue the worker generates for the firm. Published academic studies have indicated that athletes in college football, men’s college basketball, women’s college basketball, softball, and women’s gymnastics have most definitely been exploited. The current legislation does allow universities to pay more to athletes than the cost of attendance. But that pay is going to be capped and there is no mechanism that allows athlete compensation to rise as revenues inevitably rise. Again, the NCAA exploited its employees for more than a century. If players cannot negotiate the size of the cap, that exploitation will most definitely continue in the 21st century. And that means, a vote to exempt the NCAA from the Sherman Act is simply a vote to ensure the NCAA continues to exploit thousands of college athletes.
2. College sports is a thriving business
Proponents of the Protect College Sports Act like Senator Cruz claim college sports are in chaos. Yet the NCAA also argues that revenues for college sports continue to grow. In a 2026 Sports Business Journal article, Ben Portnoy wrote that the NCAA itself had indicated that NCAA revenue had grown $300 million since Charlie Baker became NCAA president in 2022. This revenue increase has happened in the “chaotic” world of NIL payments.
3. Non-profits do not earn profit
The NCAA has historically argued that we shouldn’t focus on revenues, but instead on profits. According to the NCAA, most college sports teams are not profitable. This is an immensely silly argument. College sports exist within an institution (college and universities) that are non-profits. Non-profits do not make a profit. Yes, this should be immensely obvious. Surprisingly, when the NCAA says college sports are “not profitable,” we don’t have enough people screaming: “Of course they are not profitable. You are a non-profit. There is no profit in a non-profit. It’s right there in the f—king name!”
4. College sports spend too much money on coaches and facilities
Non-profits will spend all their revenue. In fact, if the institution allows them to, college sports—just like any other academic department—will spend as much money as the institution allows. In college sports, that spending has generally been on the employees who people are not paying money to see. Instead, the money has been spent on lavish facilities and salaries for coaches.
Perhaps the clearest example of the latter is the University of Alabama in 2007 agreeing to pay Nick Saban a salary similar to what he was being paid by the Miami Dolphins. An NFL team earns immensely more revenue than the richest college football teams. Back in 2007, the Dolphins had four to five times the revenue of the University of Alabama. But because Alabama didn’t have to pay the employees who actually played football (beyond the cost of attendance), they could offer Saban very similar money. Congress has shown no interest in capping the pay of college coaches. They won’t even cap the pay of college coaches who are no longer coaching college football. And that amount can be substantial. By week ten of the 2025 football season, colleges had already agreed to pay $185 million to fired coaches who were not employed anymore. Once again, college departments will spend any money you let them spend. And in college football, spending $185 million on fired coaches is approved while people get quite upset about money spent on the employees on the field.
5. Restricting wages is not necessary to create competitive balance
The NCAA argues it must restrict wages to its playing talent to maintain competitive balance. It argues that unrestricted spending will allow the richest schools to dominate college sports. Anyone who has ever looked at the history of college sports would have a hard time believing this story. There are currently more than 360 schools that participate in Division I men’s college basketball. Since 1939, the men’s basketball season has concluded with the NCAA tournament. After the 2026 season, there have been 87 tournaments and therefore 348 Final Four teams. Given the NCAA’s persistent emphasis on competitive balance, one might expect many of the more than 360 schools participating in Division-I men’s college basketball to have appeared in the Final Four at some point in their history. But across these 87 seasons, 268 Division I schools have never had a Final Four appearance. Thus, 73 percent of the schools in Division I men’s college basketball never appeared at a Final Four.
We see the same pattern in college football. The NCAA reports champions in college football back to 1869. Across more than 150 years of history, there have been 27 schools that have won (or shared) three or more of these titles. These 27 schools have won 88 percent of these titles. As I detail in my sports economic textbook, one can see the same pattern in many other college sports.
6. College sports accounts for a modest share of university revenue
The Ohio State University is one of the biggest entities in college sports. In 2025, this school reported $8.5 billion in revenue for the institution. It also reported $336 million in revenue for college sports. If you do the simple math, this means college sports at Ohio State are less than four percent of the institution’s revenue. It is a similar story at most institutions. Yes, collectively college sports are a billion-dollar industry. But relative to the higher education industry—that is, the business in which universities and colleges actually participate—college sports is a very small business. One would think given the relatively small size of college sports, when it comes to universities, a collection of Senators would find more time to talk about non-sports matters.
But that is not what’s happening. At least, that’s not what’s happening for now. For more than a century, Congress decided to ignore the fact that the college sports business was violating the Sherman Act. Congress decided it was not a problem for an entire industry to conspire to exploit its workers. In 2021, the U.S. Supreme Court finally said this had to stop. As Justice Brett Kavanaugh said in NCAA v. Alston: “Nowhere else in America can businesses get away with agreeing not to pay their workers a fair market rate on the theory that their product is defined by not paying their workers a fair market rate.”
After this decision, the pay to college athletes started to rise. And suddenly, college sports is in chaos. Suddenly, competitive balance in college sports is threatened. Suddenly, Congress must intervene so this relatively small business can make sure it never has to pay its employees a “fair market rate” while allowing college coaches to continue to collect millions for not working. College sports is not in chaos. But if athletes continue to demand higher salaries, the pay of coaches and other administrators will eventually be threatened. In the end, the Protect College Sports Act is poorly named. An antitrust exemption for college sports allows the NCAA to protect the pay of the non-athletes employed in college sports. The Senate didn’t vote to protect college sports. What they voted for was a bill to make sure friends of Nick Saban keep getting paid.
As the calendar flipped from 2021 to 2022, orthodox economics found itself on the back foot. The all-knowing oracles of the neoliberal order were beset by unforeseen global conditions.
The COVID-19 pandemic unleashed a series of economic shocks that broke the delicate balance of globalization we took for granted. With modern trade and technology, supply-chain frailty had become ever less of a concern, shoved further and further down the policy priority list. The global inflation that terrorized working people in the 1970s and 1980s was reduced to a memory. For half a century, deregulation had accompanied prosperity (albeit inequitably distributed), masking the brittleness undergirding the modern neoliberal economy. It is worth bearing in mind that this vulnerability was intentionally manufactured; cutting redundant backups was an opportunity to reduce overhead (along with the labor share) and increase operational efficiency. Capacity investments that are held in reserve don’t generate revenue, so cutting them can function as corporate stat-padding.
As this system fell apart amidst a global pandemic, unorthodox economists long pushed to the discipline’s fringe finally found an opportunity to make themselves heard. Out of this opening emerged both Lindsay Owens’s Gouged:The End of a Fair Price–and What That Means for Your Wallet (Viking, September 2026) and Isabella Weber’s Anti-Fascist Economics: In Defense of Affordability, Dignity, and Democracy (Random House, October 2026).
These two books are a pleasure to read and review, not only because they’re both good (which they are!), but also because they come from two people who I deeply admire. They helped me to recognize that economics need not be doctrinaire, and that there is a much greater wealth of thinking about the world than you get in micro and macro classes.
They also are especially relatable to me because, in my own (much less significant) way, the story of how I came to do the work I do overlaps with Owens’s and Weber’s rise to prominence surrounding inflation dynamics. The first op-ed I ever published on my own (as a bright-eyed intern) was an argument that, contra the teachings of Larry Summers, consolidation creates the dynamic for rent-seeking to cause upward pressure on prices. So it was great fun to be along for the ride in that small way.
The deregulation of the 1970s and 80s was accompanied by a coup in the war of ideas. Neoliberal deference to markets quickly became hegemonic across the halls of power in the United States. In time, the United States forced neoliberalism down the throats of developing countries as well, through punitive international finance agreements and sometimes even violent force.
But in the pandemic’s wake, the ground underneath mainline, neoclassical economic theory and policy was buckling. Inflation—a dragon long since slain in the United States—roared back with a vengeance, fueled on by cascading macroeconomic shocks. And as the neoclassical economists floundered, new heterodox thinkers stepped up to the plate, offering new (and old forgotten) insights into the mechanics of the modern economy.
Providing for the General Welfare
Both Gouged and Anti-Fascist Economics are part of a growing canon that flips neoliberalism on its head. In what I’m calling a tradition of general welfare economics, Owens, Weber, and an increasing number of other writers and scholars articulate a vision where economic policy is designed around directly serving people, rather than around optimal efficiency and growth. This vision will be familiar to those versed in socialist thought, but is in no way inherently socialistic. While Weber describes the tradition she writes in as “one of democratic and liberal socialism,” Owens articulates the conflict in her story as “The end of a fair price undermin[ing] honest markets.” Owens’s primary recommendation is a shopper’s bill of rights, not exactly a sweeping rejection of private enterprise. (Although her prescription is not incompatible with the more socialist strain of thought either.)
Weber, Owens, and company are the successors of an economics that has been largely dormant for decades. As Weber describes, emphasis on the common good used to be commonplace in the discipline. For much of the 20th Century, economists cared a great deal about ensuring an economy that served the public interest and felt fair to participants. The new common welfare economics has no shortage of influences to draw on: John K. Galbraith, Karl Polanyi, Thorstein Veblen, Louis Brandeis, Franklin Delano Roosevelt, and E.F. Schumacher all articulated such a vision.
While such thinking was sidelined, that care for the public good never fully disappeared. Figures including James Galbraith (John’s son), Robert Reich, Marianna Mazzucato, Joseph Stiglitz, Jayati Ghosh, and Robert Pollin have been holding down the fort.
As Weber writes, “It took a whole army of economists to reinvent economics and overturn the interventionist policy lessons of World War II. Milton Friedman, the Chicago economist and fierce critic of government intervention, was this army’s top general.” Owens and Weber are among the ranks of a new heterodox top brass, marshalling strength to topple Friedman’s successors and F.A. Hayek’s bastards. Their pair of new books serve a dual purpose, acting as both a clarion and a strategic blueprint.
The two books are facially very different. Where Gouged is snappy and grounded, Anti-Fascist Economics can often be sweeping and philosophical. The former’s subject is the mechanics of corporate pricing, while the latter’s is the nature of democracy and how to build an economic framework in service to it.
Yet the commonalities between the two volumes are myriad. Both find their origins in a viral post on Twitter, an op-ed in prominent papers, and unglorious work on inflation combing through corporate earnings calls. Both were (somehow, miraculously) written by mothers of young children. Both ground their message in a historical account of economic policy. And both intersperse snippets of first person backstory describing the authors’ involvement in the great “greedflation” debate of the early 2020s–a term propagated by neoliberals like Jason Furman and Catherine Rampell to mock the notion that a company’s conduct could be responsible for contributing to inflation.
Of the two, Gouged is the more relatable and fun. While both conclude with thoughts on how to address the issues they detail, the recommendations in Gouged include things that any reader can actually do about it. It is also the shorter and more digestible of the two. Anti-Fascist Economics, on the other hand, is the more serious effort at tackling crucial philosophical questions surrounding the modern economy.
The Subjective Function
“In economics, the public good is a correction,” an adjustment captured in externalities, as the economist Mariana Mazzucato put it on X (nee Twitter), promoting her own recent addition to the canon of general welfare economics. But perhaps we need an economics where “The common good is not a correction but an objective, where all relationships embed it from the start.”
The in-the-weeds work of (especially micro-) economic theory usually revolves around actors making constrained decisions to optimize their “objective function.” Those objective functions are usually profit-seeking or cost-minimizing. Could we create a framework where powerful economic actors are instead corralled into acting in ways consistent with maximizing fairness or democracy?
Both Owens and Weber indicate that the answer could be “yes.” Owens cites to some examples of corporations opting not to ring every last dime out of their customers and even proactively operating under an ethic of civic responsibility. Using Home Depot as an example, Owens points out that the company preemptively surges extra goods to areas hit with natural disasters rather than gouging the ravaged communities. Weber sketches an expanded role for a proactive government to single-mindedly pursue an agenda of providing universal access to the necessities. Neither vision is conducive to the financialized ethos of doing everything possible to maximize profit margins (aka shareholder welfare) that has permeated corporate culture since popularized by Jack Welch at General Electric.
Some proponents of neoliberalism will retort that while well-intentioned, such efforts only undermine the ability of free markets to allocate resources efficiently, which would be more welfare-enhancing. Under that view, such an approach would inherently yoke policy to less measurable, more subjective goals. We can measure GDP and wages and inflation and job starts. We have an entire sprawling public infrastructure dedicated to quantifying such things, supplemented by an enormous private industry offering curated data and insights. Some would argue that because growth is generally good and because it is quantifiable, we should center it in policymaking in the name of objective results.
The biggest problem embedded in this approach, however, is that focusing on these “objective” metrics can obfuscate the reality of people’s lives as they move through the economy in their daily lives. Recall the discourse around the “vibecession;” many economists and pundits thought poor economic sentiment flew in the face of a strong economy. But the sentiment gap is understood easily enough when you recognize that what macroeconomists are measuring does not actually line up with a lot of what people are complaining about. Tackling inflation via interest rate hikes can make sense to an economist but still be punishing for working people who incur more expensive consumer credit and housing.
Beyond the mismatch between statistical measures and household budgets, the traditional neoliberal agenda completely writes off how the economy feels to the people comprising it. The central story that both Weber and Owens tell is one of disempowerment. They both present compelling cases that power imbalances are resulting in a punishing crisis of agency. And that we need to reorient our economic thinking to tackle those harms.
We Are the Economy
The tagline for Groundwork Collaborative, the think tank Owens heads up, is “We are the economy.” This is the central contention that unites Gouged and Anti-Fascist Economics; the economy is us.
To Weber, the neoliberal ascendence in the 1970s pushed government policy away from an active emphasis on providing a basic level of economic welfare to all of its constituents. The coup de grace in neoliberalism’s triumph, at least in Weber’s account, was Friedman’s 1977 Nobel Prize. This was a watershed moment because it capped off years of neoliberalism’s rise in policy and academic circles, just as it sidelined older schools of antitrust and Keynesian economics. The philosophy’s rapid ascendance, boosted by a coordinated corporate effort to shift economic and legal thought towards libertarianism, resulted in a widespread acceptance of the Chicago School’s central premises as the “common sense” findings of economic science.
The persistence of neoliberal thought owes much to deference to economic expertise; after all, these Chicago School economists were highly-trained scientists! When it comes to many questions of economic governance, however, it is actually impossible to come to an objective “best” policy. Macroeconomics has been effectively deployed to cloak neoliberal, free-market dogma with “no mention of vested interest, no ideology, no political agenda, no class alliances, no power structures,” as Weber describes it.
I’m personally more sympathetic to the idea of economics having a foundation in scientific principles than Weber; I think that much of our fundamental economic behavior is downstream of physical realities like entropy, which is why, for instance, the Law of Demand can be observed in primates. That said, the broader dynamic that Weber outlines as a way for scions of the Chicago School to gild their ideological preferences in scientific slogans is very accurate.
Former IMF chief economist Olivier Blanchard recently complained that while “most people, smartly, do not try to engage and question medical researchers. Unfortunately, this is not true for economics. Many too many self-appointed experts, including among politicians.” Setting aside that we are currently overrun by medical skeptics (that was the whole anti-vax thing), there are a lot of problems with this sentiment, not least that economics certainly is not scientific in the same sense that medicine is, as indicated by the discipline’s abysmal replication rate. Not to mention how fundamentally anti-democratic such a sentiment is.
Moreover, what is required for a healthy economy is much more a matter of preference than what makes for a healthy body. To most mainstream economists, a wealthier economy is inherently preferable. But many people do not actually prioritize total productivity or maximal income and wealth. We care about other concerns including dignity, equality, personal freedom, meaningful relationships, and beauty. A nation that chooses to forgo extra growth to prioritize minimal inequality, protect people’s physical and mental wellbeing, or preserve natural landscapes is not making an unhealthy decision if that is what its people prefer.
Owens details a narrower path to powerlessness, laying out how corporations have increasingly weaponized information asymmetry to exploit consumers, leaving us experiencing the economy as a never-ending series of extortions, watching helplessly while necessities drift further out of budget.
In what is probably the greatest gap between Weber and Owens, Gouged includes insights from behavioral science as one of the key ways corporations have been able to build up internal capacity to maximize the rents they can extract. To Weber, the notion of economics as a scientific endeavor is a way to conceal ideological priors. To Owens, it is precisely because of scientific discovery within behavioral economics that companies are able to exploit our powerlessness.
While both books are grounded in a vision of humanized economics, Weber’s articulation can still feel foreign and distant at times. Theorizing about how to navigate the way we encounter the economy does take away from being able to draw clear parallels between the story she tells and things that are readily recognizable to an average reader. Anti-Fascist Economics will frequently invoke necessities and affordability crises, but they are almost universally then rolled up into a grander narrative about a struggle between economics built to serve democracy and one built to serve capitalistic markets. And there is certainly value there! Much of it is a compelling accounting of economic thought and anyone interested in the history of ideas or theories of democracy will find it invaluable.
What Owens manages to do far better in Gouged, though, is to ground the loss of agency in things to which everyone can relate. A lot more people will see their lives reflected in her accounts of price manipulation, spiking rents, or “dark patterns” interface designs that “make it easy to get in, but nearly impossible to get out” of subscriptions than will be able to relate to tracing the intellectual legacy of Karl Polanyi (which is not a small part of Weber’s work). Gouged is approachable and digestible, and a typical reader will find themselves better informed about how they fit into the economy for having read it.
That is not to say that Owens does not include economic history. But where Weber embeds lived experiences that can resonate with people into a discussion of economic theory and systems of government, Owens embeds economic history into stories of lived experiences.
The Economy Is Society
Tucked away in the middle of a long paragraph in Anti-Fascist Economics (Weber is handily the more verbose of the two) is a quietly profound sentence: “The economy, ultimately, is society.” That sentiment is at once obvious and radical. For decades, economics has cordoned itself off from politics, government, and other social institutions as different bits of what was once called political economy came to be separated into new disciplines. But obviously in a broad sense every social relationship is also an economic one. When you cook your friend dinner, you change their consumption patterns and infinitesimally reduce GDP. When a loved one helps you talk through an emotional tempest, you see more clearly that the sky is not falling and that life continues. To econ nerds, you could describe that phenomenon as reducing your “discount rate” for future time periods.
Perhaps not surprisingly, making the leap into a systemic discussion of people’s economic powerlessness is where Weber outpaces Owens. In much of Gouged, people are reduced to consumers. The book is an account of “the corporate boardrooms where pricing decisions are made” versus their customers. Gouged aims to equip “us with the essential knowledge we need to first recognize, and then sidestep the traps that corporations try to conceal from us” and advertises itself as an essential aide for “anyone looking to stay an informed consumer.” There is one chapter that discusses algorithmic wage-fixing and how corporations short-change their workers that starts to flesh out the complexity of economic life, but it comes all the way at the end. It feels somewhat appended. The entire book to that point was all about consumers, then it pivots to workers, and then goes straight into the conclusion, which again focuses almost entirely on the consumer side.
In Owens’s defense, her coverage of employment is valuable, and my critiques are quibbling with details. At only 176 pages, it is hard to imagine a much more graceful way of including the employment chapter. In any case, Gouged equips the reader with invaluable information about how to better navigate the economic system we move through every day.
Weber’s aim is more ambitious, plotting out an entire economic system that reorients both the discipline and the state itself towards serving an ideal of democracy. The reader gets a laundry list of policies as Weber does a one-woman rendition of Bretton Woods, sketching out the contours of wholesale reform across trade, the energy industry, healthcare, housing, and more. The goal is nothing less than saving the world.
The first two-thirds or so of Anti-Fascist Economics walks through the case that fascism is on the march across developed countries because of neoliberal economics divorcing people from the base level of dignity and wellbeing that they need to feel like a valued part of society. Weber resurfaces insights from liberal economic titans like John Galbraith and Karl Polanyi, and then integrates their models of democracy with contemporary discussion of the far right’s ascendance, particularly Naomi Klein’s and Astra Taylor’s articulation of “end times fascism” (the title of their own recent book), where overlapping climate, economic, and geopolitical crises have instilled a deep seated nihilism in the public, who are more susceptible to narratives that provide an enemy to channel their frustration.
An anti-fascist economics, at least in Weber’s description, is inherently an intersectional economics. It recognizes and grapples with the fact that economic policy will collide with social hierarchy and systems of oppression. It challenges us to consider that unless anti-fascist is also anti-sexist, anti-racist, anti-elitist, and so forth, the “fascist virus” will have hosts in which to incubate. As the great philosophers of Chumbawumba teach in “The Day the Nazi Died,” fascist tendencies were not vanquished, they merely moved to the outskirts of society, ready to spread as soon as the conditions became favorable again.
Rather than merely wanting to hold fascism at bay and buttress existing liberal institutions, Weber wants to marshall a whole-of-society effort to stamp out the conditions that enable it in the first place. That means tackling climate change, ensuring economic equity, and building countervailing powers (hat tip to John Kenneth Galbraith) to check each other’s actions and ensure pro-social behavior. Her proposition is that the moment we are living in right now will present an opening for rapid, massive economic reorganization. She points to some case studies, headlined by Zohran Mamdani in New York City. But the vision articulated is not just a pitch for the Mamdani administration and other progressives in power, it is laying stake to all current and future policymakers’ imaginations as we head into the years that will test whether liberal democracy can continue. Particularly to a potential Democratic trifecta, the pitch is to one-up Franklin Delano Roosevelt’s New Deal.
Economics as if People Mattered
Both Anti-Fascist Economics and Gouged help to flesh out a heterodox way of thinking about economic policy, one where the general welfare is not an adjustment tacked on at the end of policymaking, but the entire point. The growing body of work to which Owens and Weber are contributing is the successor to Schumacher’s outline of “economics as if people mattered,” the subtitle of his hit Small is Beautiful. Both leave the reader with a better understanding of how we came to live in the economy we inhabit.
Owens tells an eminently readable and relatable story about the rise of corporate pricing strategies and how it shaped the way we all shop. It’s impossible to read her book without recognizing something that pissed you off in nearly every chapter. Weber offers an account of the intellectual and political tides in which these strategies are swimming. They pair very well, together providing both a human and a systemic vantage point overlooking the rot in our socioeconomic system.
We are witnessing the collapse of antitrust enforcement at the federal level under the second Trump administration. State enforcers have attempted to fill the void. But absent a muscular federal cop on the beat, state efforts will often be in vain. The exceedingly weak settlement between Paramount and the states, announced on Monday by the attorney general of California, illustrates this dynamic. In return for dropping their merger challenge, the states secured the creation of an editorial board, appointed by Paramount CEO David Ellison, to monitor the content of CBS and CNN. In other words, the states got nothing.
Why fold when you’re holding a strong hand? The post-merger concentration levels in wide theatrical film releases satisfied the requirements under the Merger Guidelines to create a presumption of anticompetitive effects. Despite these findings, the Department of Justice (DOJ) Antitrust Division officially closed its investigation into Paramount’s acquisition of Warner Bros. Discovery in June. According to The Wall Street Journal, the career staff were “leaning moving toward recommending a challenge” but were overturned by senior DOJ officials. A shareholder lawsuit alleged that Trump interfered on behalf of the Ellison family, which has contributed significantly to Trump’s campaigns over the years.
Not only did the DOJ refrain from pursuing the merger, the agency actively worked in support of the merger, filing motions against the states, including one seeking that the states “post a proper bond covering the costs of any delay” in completing the deal. From a judge’s perspective, DOJ’s active support of a merger could cast doubt on the merits of the states’ claims. How could an expert federal antitrust agency see things so differently?
The payoff for Trump for intervening in these affairs potentially extends beyond campaign contributions. Last year, concurrent with its attempt to receive clearance of its acquisition of Skydance, Paramount reportedly agreed to pay Trump $16 million as part of a settlement of Trump’s lawsuit concerning “60 Minutes.” The acquisition was later approved by Trump’s Federal Communications Commission (FCC). Some have speculated that another payoff is that Paramount will remake CNN, which is hardly progressive in its current state, into the image of Fox News.
Trump’s interference in the DOJ’s investigation likely led to this week’s dreadful outcome with Paramount. Alas, the administration’s deal with the Hollywood giant is only one example.
Across multiple industries, in exchange for regulatory favor, companies have purchased Trump’s cryptocurrency, contributed to his inaugural fund, silenced a late-night talk show host, or simply paid cash for his various vanity projects. A July piece in The Wall Street Journal spelled out the precise channel by which Trump could be compensated for a deregulatory intervention: “Trump has been demanding large checks from companies for a range of political and legacy projects—telling executives and lobbyists that their companies should give $25 million or $50 million.” The story, which was hardly news in our corruption-laden era, did not make the connection to Trump’s interference in antitrust matters before the DOJ. But it provided a related episode of a tobacco giant, Reynolds American, explicitly buying off regulatory scrutiny from a different regulator:
At a meeting with tobacco executives in May at Trump’s golf club in Jupiter, Fla., the president promised to do much of what executives wanted on policy related to vaping and the Food and Drug Administration. He also took in millions of dollars in contributions for his political committees. O’Rourke [Trump’s chief fundraiser] sat in on the meeting. Shortly after the meeting, the FDA lifted restrictions on some flavored vaping products, and the FDA’s chief was gone.
There is no reason to think that special favors in the antitrust realm would work any differently.
Other recent DOJ settlements reviewed below reveal that companies are hiring Trump allies and using various indirect mechanisms to influence antitrust outcomes. Those efforts may fall short of direct monetary payoffs to Trump. But corruption is not a binary variable. What we are observing today can easily progress towards direct payments of cold hard cash tomorrow, if that’s not happening already.
A Quick Review of Recent DOJ Settlements
In several high-profile cases, the DOJ’s Antitrust Division has pulled back from enforcing antitrust laws at the behest of Trump (and whatever lobbyist caught his ear that day) after initially filing lawsuits or opening investigations. It bears repeating that there is zero evidence, at least not yet, of money having passed to Trump; the evidence instead shows money passing to a Trump ally who brokered a back-door deal.
- Live Nation: In May 2024, the DOJ, along with 29 states plus the District of Columbia, filed a complaint against Live Nation, alleging monopolization of various concert and event-related services. After a reported personal intervention by Trump, the DOJ unexpectedly reversed course and settled in the middle of a jury trial. The states, now acting alone, persisted and secured a jury finding of antitrust liability in April 2026, suggesting the merits of the DOJ’s original case were sound.
- HPE-Juniper: In late January 2025, ten days after Trump’s second inauguration, the DOJ filed a complaint to stop the merger of two large enterprise tech companies, Hewlett Packard Enterprise (HPE) and Juniper Networks. HPE hired lobbyists, such as Mike Davis, a staunch Trump ally, who negotiated directly with aides to then-Attorney General Pam Bondi, bypassing the DOJ’s career antitrust lawyers. It was money well-spent, as the DOJ ultimately reversed course and settled the case in June 2025. In Tunney Act hearings on the settlement, the district court found the proposed settlement to be in the public interest, despite the evidence of corruption. (Read Darren Bush’s excellent Sling piece for a review of how the court erred.)
- Compass-Anywhere Real Estate: In October 2025, the DOJ was investigating Compass’s proposed acquisition of Anywhere Real Estate, first- and second-biggest U.S. brokerages, respectively, by volume. Compass hired Davis, on the acquisition, who reportedly appealed to then-Deputy Attorney General Todd Blanche’s office that the merger did not warrant a second request for information, over the objections of Assistant Attorney General Gail Slater, head of the antitrust division at the time. The deal closed at the beginning of this year without a second request.
In each of these instances, career staff, tasked with enforcing the antitrust laws and often with decades of experience of doing just that, have been sidelined by their politically appointed bosses. Indeed, reporting in The Wall Street Journal suggests that Trump has directly entangled himself in these matters. For instance, the CEO of Live Nation CEO, Michael Rapino, reportedly visited the White House twice (once with Trump himself) in the lead up to the DOJ’s course reversal. Given Trump’s transactional nature, it is reasonable to infer that he only does something if he stands to benefit. So what explains his personal involvement in any antitrust matter?
If Trump and his DOJ appointees, like AAG Slater, were libertarian, as some prior Republican administrations, then the DOJ’s unwillingness to enforce the antitrust laws could be chalked up to ideology rather than corruption. But Trump’s crowd is decidedly interventionist—and not just when it comes to tariffs or government equity in companies. They even campaigned on populist ideas that at least suggested some promise to enforce the antitrust laws. A president cannot extract a payment from a corporate giant unless and until he feigns interest in enforcing the antitrust laws; the credible threat of enforcement serves as leverage. In sum, Trump created the perfect fact pattern for a quid pro quo.
Non-cash payments can also complete a quid pro quo. The Nexstar-Tegna merger, which the DOJ did not even bother to challenge, would allow the combined entity to reach approximately 80 percent of U.S. television households; such levels vastly exceed the long-lived 39-percent cap set by the FCC. (In August 2026, the FCC’s broadcast ownership rules were relaxed on a 2-1 vote.) Some reporters have speculated that Trump’s payoff there, in return for permitting Nexstar to flout the cap, was Nexstar’s silencing Jimmy Kimmel on its affiliated networks. Eight states sued to block the Nexstar-Tegna merger, and a federal judge halted the deal in April, indicating the merits of such a challenge were sound. A trial date on the matter is set for July of next year.
Comfortably Numb
Consistent with Steve Bannon’s theory of flooding the zone, the unending stream of this administration’s corruption has caused previously presidency-ending activities to seem hardly worthy of a footnote. Trump’s repeated market-moving announcements of the start (or end) of the Iran War—a conflict that has killed as many as 22 American service members and over a 3,000 Iranian civilians—have provided myriad opportunities for insiders to cash in, as the price of oil (and the stock market generally) have predictively moved in response to Trump’s manufactured events.
If that weren’t bad enough, Trump now offers a premium version of Truth Social that allows early access to his market-moving announcements. Trump is seeking to monetize the office of the presidency in broad daylight.
In the face of such blatant corruption, it is natural for us all to go numb. Even if a reporter were to identify an explicit payment to Trump in return for an antitrust waiver, it is not clear whether that act would spur Democrats into action, as many corporatist Democrats enjoy the same patronage as Republicans.
So who cares about corruption? Well, if you don’t believe in antitrust enforcement (think Matt Yglesias and his ilk), and you learn that the president (hypothetically) has been monetizing his powers to terminate antitrust investigations, then you likely will not be moved by news of the monetization. This is just the price of getting deals done. Who cares if the president gets to wet his beak?
If, on the other hand, you believe in antitrust enforcement, and you learn that the president (hypothetically) has been monetizing his powers to terminate antitrust investigations, then you also likely will not be moved. What upsets you is the lack of enforcement; that Trump may have personally benefited from the decision to settle a case is of secondary importance. Absent the executive meddling, however, enforcement would have continued; in this case, the purported monetization was pivotal to the outcome. Moreover, to the extent that career officials at DOJ or FTC perceive that any meritorious case can be reversed at the eleventh hour (via a Trump intervention, compensated or not), fewer cases might be developed. Why invest the energies and resources if the process is ultimately rigged?
It’s possible that those who hold no views on antitrust enforcement—potentially a large swath of Americans—upon learning that the president (hypothetically) has been monetizing his powers to neuter antitrust investigations or active cases, would be freshly upset by news. It might seem unjust that only the largest (and unscrupulous) companies can purchase their way around law enforcement. As affordability becomes a central political issue, voters might connect consolidation and exploitation (in the case of Live Nation) with higher prices.
But would enough people care about the news to demand Congressional inquiries and passage of legislation that would prevent future presidents from monetizing their powers? There are some indications that blatant corruption could move voters. A milder form of corruption occurs via campaign contributions, by which large corporations made contributions in exchange for an implicit promise for hands-off treatment. At least three Senate candidates — Abdul El-Sayed (Michigan), James Talarico (Texas), and Jon Ossoff (Georgia) — have campaigned on a pledge to eradicate this form of corruption. One could imagine explicit corruption easily being folded into their campaigns.
The Key to Meaningful Reform
As an alternative strategy to acquiescence, we can try to restore the democratic principle that antitrust law applies equally to all firms, regardless of political influence. How can we do that? One can look at attempts at political reform to curb executive overreach in the post-Nixon era, including how they fell short. In 1974, Congress passed the Election Campaign Act Amendments, which overhauled campaign financing by setting strict limits on political contributions and expenditures.
In the same year, Congress passed the Tunney Act, in response to perceived meddling by the Nixon administration into the DOJ’s investigation of ITT’s acquisition of the Hartford Fire Insurance Company. As Darren Bush recounts in The Sling, ITT “offered to help finance the 1972 Republican National Convention. While no quid pro quo was proven, the appearance of impropriety sparked significant debate.” In 2004, Congress revised the Tunney Act to compel a public interest determination. But we’ve already seen in HPE-Juniper why the Tunney Act is insufficient, at least in its current form, to protect against presidential meddling. Courts have shown uniform reluctance to question proposed final judgments, or engage in anything more than performative questions before using the rubber stamp.
None of these Nixon-inspired safeguards, to the extent they even resemble what Congress intended, prevent Trump’s effort to sell regulatory waivers to the highest bidder. Trump’s abuses make Nixon’s appear quaint by comparison. The rationale for making the FTC an independent agency, as opposed to an executive one, was to insulate career officials from executive interference. There is little wonder why Trump is trying to convert the FTC into an executive agency, by firing its two Democratic commissioners. Alas, the Supreme Court seems pliant to this usurpation of power, making a special exemption for the Federal Reserve to remain independent but not the FTC.
Despite his timid approach to price gouging and other corporate abuses, President Joe Biden never sought to unwind an FTC or DOJ antitrust investigation. We can either hope to elect presidents who respect the independence of antitrust agencies, or we can build in certain protections against future abuses. In an ideal world, we can make the FTC independent again, with full authority and resources to prosecute antitrust cases ignored by the DOJ. And even within the DOJ, we should have a law ensuring that once a political appointee such as Abigail Slater or Jonathan Kanter decides to open an antitrust inquiry, those leaders and supporting career officials are shielded from executive interference.
Finally, we need to stop the revolving door from agency to lobbyist. Some of the worst abuses here occurred under the Obama administration. After “investigating” Big Tech, many of Obama’s FTC appointees landed jobs in Big Tech. Working for the DOJ or FTC should be career paths with much higher compensation. They cannot be stepping stones into cushy jobs defending the same conduct they were previously tasked with policing.
There are ways to prevent future presidents from monetizing the White House. The meager settlement between the states and Paramount is the latest consequence of the Trump administration’s evisceration of antitrust enforcement. If we fail, we will continue to experience the concentration of power in the hands of a shrinking set of oligarchs.
In the heart of Hollywood, Paramount Studios sprawls across a 65-acre campus, housing hundreds of thousands of square feet of offices, sound stages, sets, and a five-acre replica of the streets of New York City. Paramount directors and producers have filmed, soundtracked, and edited many thousands of films and television shows in its Los Angeles home for more than a century. The studio’s history and physical presence embody Hollywood.
The threat that Paramount might pull up stakes and leave the state altogether, far-fetched as it might be, became the boogeyman Paramount Chief Executive David Ellison used to scare California Governor Gavin Newsom and Attorney General (AG) Rob Bonta out of their effort to stop Ellison’s planned $111 billion takeover of rival movie studio Warner Bros. News reports described Ellison’s threat that he would move the studio to Nashville if the state continued prosecuting its antitrust lawsuit as “deadly serious.”
Paramount picking up its business and assets and leaving California has always been unlikely. As multiple former antitrust officials have pointed out, the financial impact of moving a business is something Paramount likely can’t absorb. Who’s going to work at Paramount Studios in Tennessee? Most of the entertainment industry’s top producers, directors, set designers, engineers, writers, gaffers, cameramen and actors live and work in Southern California. How would one uproot all that infrastructure, including the streetscapes? Although Nashville has a fledgling film industry, the prospect of moving all of that physical stuff and decoupling Paramount from its Hollywood home smacks of fiction — and desperation to end a legitimate challenge to a facially anticompetitive merger.
Yet that threat is what turned the tide against the state-led lawsuit to block the deal. Yesterday, Bonta and a group of 11 other state AGs backed away from their litigation and allowed the deal to close with minimal interference. Bonta’s choice to do so is disappointing, of course, bowing as they did to an empty corporate threat. But the choice also clouds a once-rosy picture of the role state antitrust plays in maintaining open markets and protecting workers, shoppers, and honest businesses from corporate wrongdoing.
Legally, the lawsuit to block the deal appeared to be on sound footing. Paramount’s purchase of Warner Bros. would have left only four major film distributors in America, accounting for around 85 percent of the industry. Prevailing Supreme Court precedent under its 1963 decision in Philadelphia National Bank says that’s beyond the level of concentration needed to support an antitrust challenge. An article in The Sling estimated the concentration index (known as HHI in antitrust parlance) for theatrical releases would increase from 1,594 to 1,938 post-merger, well beyond the threshold for challenging a merger under the current federal merger guidelines and creating a de facto duopoly in basic cable programming.
In other words, now that the deal has received a blessing from the state AGs, the merged company will wield an incredible amount of power in the entertainment industry. Cable distributors fear negotiating with a company that owns Discovery, TBS, TNT, CNN, HGTV, the Food Network, MTV, Nickelodeon, CBS, and scores of other networks. A single company controlling that much content can ratchet up what they charge cable companies–a cost the cable companies will certainly pass on to their subscribers. The merger would have a similar impact on the film industry. The combined company has the power to squeeze theaters for a heftier split of the revenues a movie makes, leading to even higher ticket prices for moviegoers.
The merger will also punish thousands of Hollywood and other entertainment industry workers. The Writers Guild of America sued to block the merger, accusing the deal of eliminating a major employer of writers and other Hollywood workers. As economists Rafay Abid and Devesh Ray explained, “If we take one bidder out of the game, then every remaining studio’s best response is to temper its bid.” Mergers often lead to job loss; around 30 percent of workers at merging companies are made redundant on average. A merger that eliminates competition for workers is just as harmful as a deal that eliminates competition for goods and services in the view of both the courts and the merger guidelines.
Despite this sound footing, and after describing behavioral remedies as “not particularly good at solving the problem,” Bonta agreed to a paltry (behavioral-remedy-laden) deal with the studios. The remedies in the lawsuit, on the surface, go some way towards addressing some harms of the merger. The studios, for example, must negotiate their rates with cable television distributors separately, rather than pooling their networks to gain bargaining power. They must maintain their current film rental rates they’ve negotiated with theaters. If the companies break those terms of the deal, they’ll be forced to sell off some of their film and television properties. The deal also protects the right of workers at the combined company to maintain union membership.
But that’s about it. The deal still exposes workers to layoffs and redundancies. The TV and film properties the companies would divest if they violate the consent agreement—the BET television network and the film studio Miramax—wouldn’t restore real competition to either the film or television markets. Most egregiously, the decree overall expires after five years, and the company would only have to maintain the rental rates it charges theaters for the first three of those years. What’s more, the remedies would go away entirely if the U.S. slips into a recession. The behavioral guardrails the decree puts in place will be gone in a flash. Then, nothing. Just the power of the combined Paramount and Warner Bros with nothing to stop it from using that power to raise prices.
And that’s not taking into account the more political goals of the merger, and the state lawsuit to stop it. Ellison is a close ally of the Trump administration, and he has already reshaped the news division at CBS. Ellison was in talks with the White House to dismiss some CNN hosts from the network if the administration would green-light the Paramount/Warner Bros deal. The Department of Justice did just that, so preserving CNN’s journalistic independence hung on the state’s lawsuit. In the settlement, Paramount did agree to establish an “Editorial Oversight Board” to oversee journalistic integrity at CNN. That board will be appointed by the company’s board of directors, of which Ellison is the chairman.
Bonta’s decision to allow the mega-merger to close bodes poorly for antitrust enforcement in California, and likely well beyond. As we’ve seen, state antitrust enforcement becomes the sole bulwark against harmful mergers and monopolies when the federal enforcers abandon that duty, as they have largely done under Trump. Although the states prevailed after the DOJ left the Live Nation monopolization case, the states lost their challenge to the AT&T-Time Warner merger, an indication that going solo can be risky. Moreover, enforcing antitrust law requires significant resources, which only a handful of big, wealthy states can marshal. California is one of them.
California’s willingness to prosecute an antitrust case to trial and beyond deters bad deals and behavior. If the federal agencies won’t step in and states with real resources like California hand out weak settlements, the current wave of anticompetitive mega-mergers will continue unabated.
The settlement is particularly problematic in California. For years, the California Law Revision Commission has been studying ways to improve the state’s antitrust law, the Cartwright Act. Much of the Commission’s work has focused on whether California needs a state-specific merger law that would allow it to stop anticompetitive dealmaking without relying on federal law and courts. The Commission is likely to recommend that the state legislature introduce and pass such a bill, but Bonta’s capitulation to Ellison and the Paramount/Warner Bros. deal casts doubt on the state’s willingness to properly enforce its own anti-merger law even if it were to pass. Plus, California Democrats accepted bad-faith, big business arguments and stripped the private right of action out of its pending monopolization bill, the COMPETE Act, suggesting the same fate may await a bill banning bad mergers. If workers and small businesses can’t enforce the law, and if the AG also won’t enforce it, what’s the point of having a law in the first place?
The settlement is a shame, and not just for the entertainment industry and the public, which will very likely face higher prices, lower wages, worse entertainment options, and even more politically compromised news media. Actors, directors, and a collection of industry and labor advocates pushed the state to fight the deal. State-level antitrust enforcement appeared to be exactly the antidote for a Trump Administration closely aligned with corporate power. Bonta’s choice to bless the Paramount/Warner Bros. deal casts some doubt on states’ willingness to ignore hollow corporate threats and fully embrace their statutory role as competition enforcers.
Ron Knox is a senior researcher and policy advocate for Institute for Local Self-Reliance’s Independent Business Initiative.
On the first of September, the Los Angeles Clippers of the National Basketball Association (NBA) received some devastating news. Steve Ballmer, the team’s billionaire owner, had been suspended for one year from all league functions for his role in the Kawhi Leonard affair.
What does this mean for the Clippers? According to the New York Times, a suspended owner faces the following restrictions: “… there is to be no attendance at games or practices—for their or any of the other 29 NBA teams. No appearances at the NBA All-Star Game or Emirates Cup, finals, draft or combine.” Indeed, suspended owners can’t even go into team offices or influence personnel or business decisions.
Or to put it simply, the Clippers are going to lose the benefit of Ballmer’s leadership. For an entire year! Again, this should be devastating. The New York Times noted that Ballmer is the richest owner in the NBA. He is one of the richest men in the world. To lose such a leader will obviously hurt.
Right?
This is a story we often hear. Business leaders are often glorified. A host of articles and books have been written celebrating various business leaders who have changed the world. Economists have actually argued that the fundamental factors of production are labor, capital, land, and entrepreneurs. Or to put this in simple words, production in the economy requires workers, machinery, land, and a person brilliant enough to put it all together. From this perspective, without the entrepreneur—or without the business leader—a business simply can’t succeed. As Investopedia says: “Entrepreneurship is the secret sauce that combines all the other factors of production into a product or service for the consumer market.”
This is not just something economists imagine. Once upon a time, Ayn Rand wrote a story about the importance of that secret sauce. That story was Atlas Shrugged. Published in 1957, Rand’s book goes on for more than 1,000 pages. For those who are not interested in reading this much (and I have!), Daniel Kowalski summarized the story as follows:
The plot of Ayn Rand’s 1957 novel Atlas Shrugged can be briefly summed up as follows: the productive leaders and innovators of the country go on strike by disappearing from society to protest the cronyism, corruption, and oppressive taxes that have made living a virtuous life unbearable. The nation is then on the brink of an economic collapse as the remaining politicians, intellectuals, and mediocre businessmen are only able to take from others and have no capability to create or add value.
In Rand’s fable, when these leaders go on strike, society collapses. If this story reflected reality, the Clippers are clearly in trouble. Once again, it looks like Ballmer is one of the “best” business leaders in the world. We have to believe that losing that sort of talent has to cause the Clippers to collapse.
If you look for stories examining the Clippers’ prospects in 2026-27, though, none seem to mention Ballmer. Stories about the Clippers—and any other NBA team—generally focus on which players the team employs (or doesn’t employ). No one mentions the role the owner plays in a team’s fortunes.
This is not just a story about the Clippers or the NBA. Let’s think about the history of strikes and lockouts in sports. A strike happens when the players refuse to show up to play. A lockout happens when the owners refuse to allow the players to play. These are not really different events. Typically, a lockout is simply an effort by the owners to move the timing of an impending strike to a part of the season that minimizes the owner’s pain. A strike at the end of the season will cost the owners the playoffs. Players aren’t paid for the playoffs, so a strike at that point costs the players very little but harms the revenue streams of the owners. A lockout at the beginning of the season harms the players (i.e., takes away their pay) and possibly protects those valuable playoffs.
Whether it is a strike or a lockout, though, the story is the same. The players do not come to work and the entire sports league ceases operation. Without the workers, there simply is no business.
Rand told a story that the same should be true for the leaders of the business. If we take away the “secret sauce” of business leadership, the business also ceases to function. Rand went every further. In her story, taking way the “secret sauce” of business leaders causes society itself to cease functioning.
If this were true, then there is a simple bargaining strategy for owners in a labor dispute with players in sports. Consider the pending labor dispute in Major League Baseball. The owners in baseball want a salary cap. The players do not. The players have threatened to go on strike to make sure a salary cap is not implemented. The owners should reply: “If you do not accept a cap on your salaries—which we know is best for the game—the owners will go on strike. We will no longer lead you. Without our leadership, baseball will collapse and you will not have a job!”
Despite what we hear about the importance of business leaders, we have never heard an owner—inside or outside of sports—make such an argument. Yes, owners have threatened to withhold investment. But that is not the “secret sauce” of entrepreneurship. Banks and stock markets exist to connect the funds of savers to the financial needs of businesses. Everyone understands that land, labor, and capital requires financing. Again, that’s one of the primary functions of the financial industry.
Business leaders, though, don’t argue they are just another form of a bank. No one has ever written a book about how a great business leader did an amazing imitation of a bank. Books are written about the amazing “leadership” of these people.
If those stories were true, then business leaders should be able to threaten a strike. And the fact they never do this gives away the real game.
The comedian Bill Burr captured this point in a comedy bit about Steve Jobs. Burr points out that Steve Jobs was celebrated for changing the world we live in. Yet Burr questioned if Jobs really did this. After all, as Burr points out, Jobs didn’t create all the technology at Apple by himself. Burr explains that Jobs just told other people what to invent. And when the product came out, Jobs took all the credit.
This is essentially what happens every time a sports team wins a title and the owner lifts up the trophy. The players won the title. The owner celebrates as if they played a huge role in this outcome. We all know, however, that the owner really didn’t win anything. In sports, it is well understood that the players win the titles.
All of this tells us that maybe economists aren’t getting the factors of production quite right. A firm requires labor, capital (i.e. machinery), and land to produce a product. This has to be true. Whether or not they truly need a “brilliant” leader… well, Steve Ballmer isn’t going to show up for work for an entire year. Do we think the Clippers are going to notice?
And this is why owners in sports don’t threaten to strike. It would be truly embarrassing if the player called their bluff and no one noticed when the owners stayed home!
Tesla’s Cybercabs have been all over the news since their viral launch in Austin earlier this month. The two-seater with no steering wheel is not for the faint of heart. But the design of the autonomous vehicle (AV) isn’t as impressive as its growth: Tesla’s fleet increased sevenfold in the three weeks before launch, and Tesla has secured permits for up to 5,000 more vehicles.
On a more optimistic note for labor, in August, Uber and Lyft drivers in California won, after twelve years of organizing, the legal right to unionize. Three chapters of the Service Employees International Union merged to form the California Gig Workers Union, which represents roughly 350,000 drivers statewide and is reportedly the largest single unionization effort in U.S. history.
Prop 22 classifies these drivers as independent contractors, a status that would otherwise block them from unionizing at all. But a 2022 appellate ruling struck down Prop 22’s ban on collective bargaining specifically, and AB 1340 built directly on that opening. The legislation’s main demands were to replace Uber’s and Lyft’s opaque and algorithm-based pay with a transparent rate card that covers the cost of driving, and to establish a fair process before a driver can be deactivated without explanation. New York City drivers already have something close to that—a pay formula that is set and published by regulators.
Surprisingly, Uber and Lyft supported AB 1340, perhaps after recognizing that their efforts to derail it were for naught. Their backing came in exchange for a separate bill, SB 371, that cut their insurance costs.
The bargaining rights granted by AB 1340 could be the first of their kind in the country to be awarded to a job that may not soon exist—AVs after all don’t require drivers, at least not in the same scale.
Credible outside options
To understand what the union won, it helps to think about where a company’s leverage in any negotiation comes from: what each side walks away with if no deal happens at all. Economists call this outcome an “outside option,” the fallback each side has if talks break down.
Right now, drivers have leverage because Uber and Lyft don’t have a real fallback. If there’s no deal, there’s no ride-hailing service in that city. That’s the same leverage any worker has when they’re the only available source of the labor a company needs.
AVs change that fallback calculus, even before they are anywhere close to replacing drivers entirely. Once a viable AV fleet exists in a city, Uber’s and Lyft’s outside option suddenly starts looking much more credible. If the union decides to walk away, the ride-hailing companies can simply say: “We’ll just use AVs to cover for you.”
But it’s not as straightforward as it looks. You would think this threat would only matter if AVs were profitable for the platforms. Why bother using them as leverage if they aren’t? But research on platform competition suggests AVs might not even be a clean win for the companies themselves. If multiple firms race to deploy fleets in the same city, then they will compete away any labor savings by cutting fares to win riders. If that sounds like good news for drivers, it isn’t.
Again, a threat needn’t be profitable to work. It simply needs to be cheaper than paying more. In game theory, a credible threat doesn’t need to be the platforms’ most profitable move; it just needs to be believable enough to change what the union can realistically expect to win at the table.
Watch the trips per hour
Per Gridwide Analytics, Los Angeles and San Francisco, the two biggest markets the new union represents, already have the largest Waymo fleets in the country. If this bargaining-power story is right, the numbers should already show an impact on drivers. Using their data, I compared various measures of output in five AV-active cities—Atlanta, Austin, Los Angeles, Phoenix, and San Francisco—against the national average.
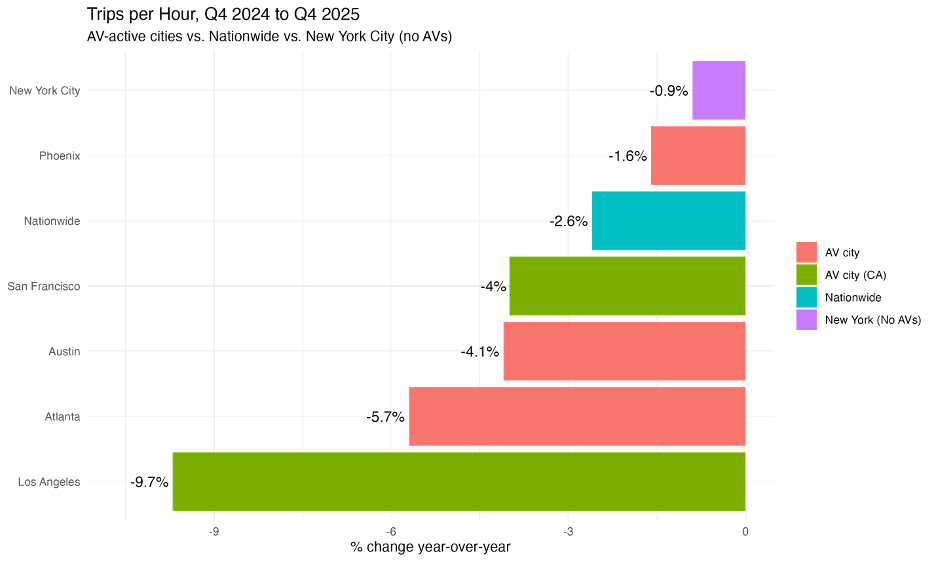
Sources: NYC TLC monthly data (New York City); Gridwise Analytics, “Autonomous Vehicles Impact Report 2026,” p. 8 (all other cities and Nationwide).
As the figure above shows, I find that trips per hour for drivers and driver utilization fell faster in every single one of these cities than nationally. Los Angeles saw the sharpest decline, with trips per hour for drivers down 9.7 percent year-over-year, more than three times the national drop of 2.6 percent. This implies that driverless rides are displacing rides with drivers.
Earnings are a different story. In some cities, such as Atlanta and San Francisco, drivers saw quarterly pay rise because higher per-trip pay and tips made up for the lost rides. In other cities, such as Los Angeles and Phoenix, that cushion wasn’t enough and total earnings fell. For now, companies are making up some of the difference by paying more per ride. But the number that matters most to the threat is how many rides are available, and that keeps falling.
An economist would probably say that correlation isn’t causation, and we don’t know whether AVs are causing trips per hour (with drivers) to decline or something totally unrelated affecting these five cities. To answer that, I used New York City as the benchmark, as the Big Apple doesn’t have any AV presence due to a de facto ban on driverless service. Using the city’s own public driver pay data, trips per hour (with drivers) has remained almost constant, down just 0.9 percent from Q4 2024 to Q4 2025.
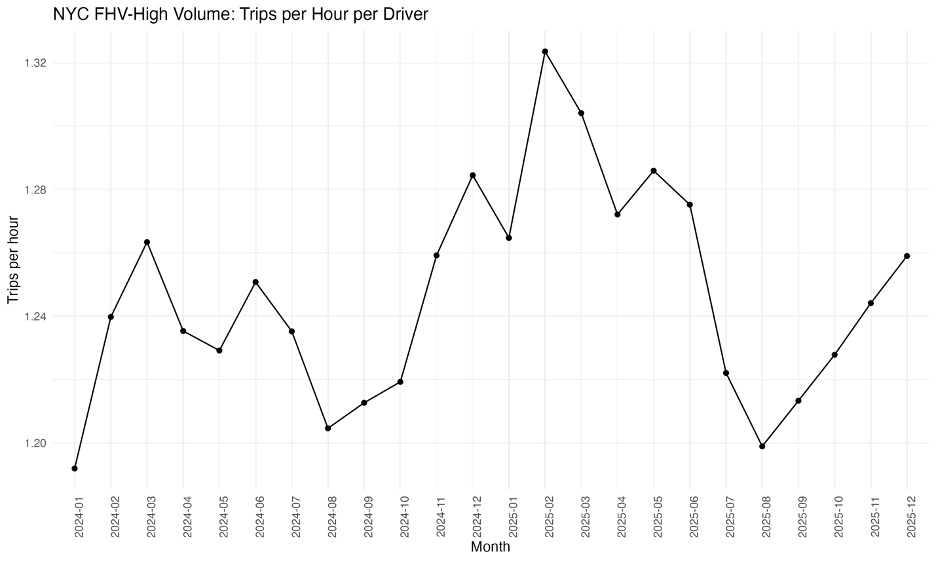
Source: NYC Taxi and Limousine Commission, monthly aggregated FHV data.
A caveat to note is New York’s pay formula already penalizes Uber and Lyft when driver utilization is low, giving the companies themselves a direct incentive to actively manage driver supply. So whatever affected those five cities would probably face higher resistance in New York, simply because the companies there have a financial reason to fight it.
Active regulation can prevent this kind of decline by making it too expensive for ride-hailing companies to let driver activity slide, even once AVs arrive. New York does this on two fronts: the city has a transparent, regulator-set pay formula, and the state requires a licensed human driver behind the wheel of any AV operating on public roads.
Waymo, Tesla, and Amazon are pushing AVs precisely to get rid of their labor force. Meanwhile, their self-driving technology isn’t perfect, causing actual consumer harm. The point of unionization is not just to provide adequate wages and benefits, but also to serve as a means to check a company’s decision-making power and prevent it from being reckless.
Maybe AVs never fully take over, and this all ends up as a footnote. But California shouldn’t let the threat of automation become an excuse to hold back on worker protections. The argument that higher wages will simply push employers toward robots is not a reason to leave workers with fewer protections. If anything, California’s decision to grant ride-hail drivers bargaining rights makes those protections more important as automation encroaches on the space once formerly occupied by humans.
Devesh Ray is an economics graduate student at Columbia University and was a summer analyst at EconOne.
Paramount Skydance says its proposed acquisition of Warner Bros. Discovery will produce more than $6 billion in savings within three years, mostly by cutting redundant corporate functions, technology, procurement, and other overhead. Those savings may well materialize. But the people whose leverage stands to change most after the deal are not the executives consolidating back offices. They are the writers, actors, directors, producers, and other creative workers whose work the combined company would buy, finance, distribute, and monetize. That is the real tension in this merger—and in the efficiencies defense across creative industries more broadly. A firm can become cheaper to run while growing stronger against the people who supply its most valuable input. Antitrust law should not credit these kinds of efficiency justifications.
Under the 2023 Merger Guidelines, a cognizable efficiency must be merger-specific, verifiable, and not itself the product of reduced competition. Since United States v. Philadelphia National Bank, agencies and courts have at times treated the efficiencies defense with suspicion. That suspicion should not be applied the same way in every industry. In creative and content markets—publishing, music, film, live entertainment, media—the efficiencies defense ought to face a materially higher bar than it does in industries where the product is homogeneous and the claimed savings are mechanical.
A different kind of efficiency
In industries with an engineering-legible product—think steel, cement, hospital services, or industrial gas—claimed efficiencies usually take the form of hard cost reductions: plant consolidations, elimination of duplicate distribution networks, procurement scale. These can be tested. An economist can examine engineering studies, historical cost data from comparable deals, and accounting records, and reach a falsifiable conclusion about whether the savings are real, merger-specific, and likely to be passed through.
In creative industries, by contrast, the claimed efficiencies are often softer: better curation, improved cross-promotion, “synergy” between catalogs, or more efficient allocation of marketing spend across a combined slate. These claims are much harder to falsify because there is no engineering baseline against which to test them.
The Penguin Random House (PRH) / Simon & Schuster (S&S) litigation remains the cleanest illustration, and it never even required a full merits trial on efficiencies to make the point. PRH’s economic expert based his analysis on projections supplied by the company’s own executives and conceded he had not independently verified the numbers. The Justice Department moved to exclude his testimony on that ground; Judge Florence Pan granted the motion before the merits trial finished. PRH had claimed the merger would generate enough savings to produce more than $100 million in additional author compensation by 2025. That is a specific, appealing figure. It is also exactly the kind of internally generated, externally unverified claim the Guidelines’ verifiability requirement exists to screen. That this happened in the highest-profile creative-industry merger challenge in a generation is not a coincidence. It is what happens when the underlying claims are inherently softer.
The efficiencies defense is designed to answer a particular kind of injury: higher prices or reduced output from diminished competition. That frame works for most goods markets. It is frequently the wrong frame for creative industries, where the theory of harm is often not about the price a consumer pays but instead about the diversity, quality, or range of what gets made at all.
Consider a merger between two of a handful of major publishers, record labels, or streaming content aggregators. The harm the government is most likely to allege is not that book prices (or records or streaming services) will rise a few percentage points. It is that fewer independent voices will get published, mid-list authors will lose outlets, and viewpoint and genre diversity will narrow because acquisition decisions become more centralized and more risk-averse. A cost-saving efficiency does not answer that harm. Even the most talented economist cannot offset “the market for original storytelling has fewer buyers” with “the merged firm’s warehouse and distribution overhead is four percent lower.”
This is a structural feature of creative markets, not an incidental one. Vertical and horizontal media deals have long tried to answer diversity concerns with efficiency claims anyway—the argument that a combined firm can invest more, produce higher-quality content, and thereby serve consumers better. Sometimes that argument may be true. But it is a quality claim dressed as an efficiency claim, and it should be treated with skepticism.
Skip the offsetting benefits
Philadelphia National Bank also stands for the proposition that a merger-induced harm to one party cannot be offset by merger-induced benefits to some other party. The PRH/S&S case is worth returning to because its real theory of harm was not about the price of books. It was about monopsony power over authors. The government claimed the combined firm would suppress advances for the exclusive right to publish anticipated top-selling manuscripts—a distinct market Judge Pan credited when she blocked the deal. PRH’s efficiencies pitch, which focused on savings in distribution, marketing, and overhead, was aimed at the wrong side of the transaction. Even if every dollar of those claimed savings had been real and verified, it would have done nothing to cure suppressed competition for author advances.
This is not unique to book publishing. Creative industries generically feature concentrated buyers and many differentiated sellers who are largely interchangeable from the buyer’s perspective: labels and artists, studios and screenwriters, ticketing platforms and touring musicians. Live Nation’s ongoing antitrust troubles—a monopolization case rather than a merger challenge, but instructive here—turn on precisely this dynamic. The government’s 2024 complaint alleged that the company’s control over promotion, venues, artist services, and ticketing let it squeeze artists and venues, not just fans. A jury agreed the conduct amounted to unlawful monopoly maintenance. The broader lesson is straightforward: efficiency defenses pitched at consumer-facing distribution economies are non-responsive to buy-side harm, and creative industries are disproportionately likely to present exactly that kind of harm.
None of this means creative industries categorically lack legitimate efficiencies. Content and platform businesses increasingly have cost structures—high fixed costs for product development, near-zero marginal costs of distribution, strong economies of scale and scope—where genuine, verifiable efficiencies are especially plausible. A streaming platform’s marginal cost of serving one more subscriber a given piece of content is close to zero; combining catalogs or infrastructure can produce real, measurable savings in licensing overhead, content delivery, and cross-platform bundling. AT&T’s defense of its acquisition of Time Warner rested on exactly this kind of claim—the elimination of double marginalization from vertically integrating a content owner with a distributor. It was a specific, quantifiable, economically well-established mechanism that Judge Leon found credible enough to help clear the deal in 2019. That is what a legitimate creative-industry efficiency claim looks like: a hard, structural, textbook mechanism.
The honest synthesis is therefore narrower than a blanket rule that efficiencies matter less in creative industries. Efficiencies defenses in these markets deserve heightened skepticism as currently pled. But the double-marginalization defense in AT&T/Time Warner shows the rigorous version is possible. The excluded testimony in PRH/S&S shows what happens by default when parties do not do the work.
It is worth pausing on why PRH/S&S became the template rather than an outlier. Book publishing has an unusually transparent record: the advance for any given manuscript is a matter of contract, and the “anticipated top-selling books” market Judge Pan credited was provable with auction data. Most creative industries do not offer that kind of clean record. Music licensing, film financing, and platform content acquisition involve compensation structures—royalty splits, backend participation, algorithmic promotion—that are harder to observe and harder to model than a book advance. If a court had this much trouble crediting an efficiencies claim in the one creative sub-industry with relatively legible pricing, there is little reason to expect merging parties in less transparent markets to clear a lower bar. If anything, the opacity of compensation in those markets should make agencies more skeptical of self-reported efficiency projections, not less.
There is also a timing asymmetry. Efficiency benefits in creative-industry mergers are almost always prospective and long-dated—that will supposedly appear over years—while the competitive harm to a concentrated seller pool is often immediate and structural, showing up in the next negotiating cycle. Courts evaluating a Section 7 challenge are not well positioned to defer judgment while a speculative benefit plays out over a multi-year horizon, particularly when the harmed party has no comparable ability to wait and see. A rigorous efficiencies standard should discount claims more heavily the further out their realization sits.
A modest proposal
Agencies and courts evaluating efficiencies claims in creative-industry mergers should apply three specific tests before giving them weight. First, is the claimed efficiency mechanically verifiable against something other than the parties’ own internal projections—the way double marginalization can be modeled independently of what executives said about it? Second, is the efficiency actually responsive to the theory of harm being alleged, or does it answer a price-based question when the real harm concerns diversity, quality, or buy-side suppression? Third, where the harm runs through a concentrated-buyer market—advances, session rates, licensing fees, artist compensation—has the merging party shown that the efficiency flows to that side of the business rather than merely to the consumer-facing side?
If the district court were to apply this three-part test to the claimed efficiencies in the pending Paramount Skydance / Warner Bros. Discovery transaction, it would likely reject the merging parties’ claims. First, the claimed savings appear to rest largely on the merging parties’ own projections rather than independently verified evidence of merger-specific savings. Second, even genuine cost savings would not address the competitive harm caused if the merger reduces competition for creative talent and leaves fewer purchasers of content leading to less content diversity. Finally, no evidence suggests any of the savings would actually flow to the writers, actors, producers, and other creative talent whose bargaining power the merger diminishes. Applied honestly, this framework does not zero out the efficiencies defense in creative markets. It disciplines it. Parties who can offer only a PRH/S&S-style unverified synergy story should lose on efficiencies, as PRH did before the merits trial even reached the question. Parties who can show an AT&T/Time Warner-style structural, quantifiable mechanism should receive the credit the Guidelines were designed to give them.
Shishene Jing is a Fellow at the Thurman Arnold Project at the Yale School of Management and a former antitrust attorney with the Federal Trade Commission Bureau of Competition Technology Enforcement Unit, where she worked on an investigation into the artificial intelligence industry. She clerked for Judge Jed S. Rakoff on the Southern District of New York and Chief Judge Robert A. Katzmann on the Second Circuit. She earned a JD from Yale Law School where she served as an Articles Editor on the Yale Law Journal and graduated with a B.A. in Economics from Stanford University. Her interests are in artificial intelligence, technology antitrust, labor antitrust, copyright, and regulation of creative industries.
The post-pandemic inflation surge generated an intense debate over the role of corporate profits and market power. One side argues that supply disruptions created opportunities for companies, especially in concentrated industries, to raise prices in coordination beyond their rising costs. The other side responds by noting that profits could have increased due to rising demand, while asserting that the ability to coordinate price hikes did not suddenly increase in 2021. A cruder version of this critique mocked the notion of corporate malfeasance under the label “greedflation,” and reminded us that greed is a constant! Maybe so, but opportunity to exercise it is not. As any investigator knows, a crime requires both motive and opportunity. Greed provided the former, while the cover of inflation provided the latter.
In a recent paper, titled “Did profits cause inflation?,” industrial organization economist Christopher Conlon advances this demand-based alternative hypothesis—a defense of corporations, really—by suggesting that for weakened competition to explain the rise in inflation in 2021-22, new cartels would have to emerge at roughly the same time: “Importantly, there is little evidence of a surge in newly organized cartels or widespread consolidation across industries during 2021–2022.” Because Conlon finds no economy-wide formation of cartels, he rejects the hypothesis that a change in firm behavior could have driven inflation.
Yet the “profit-inflation” hypothesis does not require cartels to have formed exactly when inflation surged. An industry could have been highly concentrated before the pandemic, but the opportunity to collude did not present itself until after the cost shock began. In addition to cartels, proponents of this theory, aka “seller’s inflation,” such as Lindsay Owens and Isabella Weber, explained how firms exploited a cost shock to raise prices by more than any cost increase as we emerged from Covid. Again, profiteering under the cover of a crisis doesn’t require the immediate formation of a cartel. Indeed, firms themselves were advertising price increases during earning calls, providing price signaling to their rivals—that is, a willingness not to undercut them. And the more concentrated the industry, the less the need for concerted action if unilateral exercise of market power will achieve the same goal.
Covid-related disruption created unusually favorable conditions for firms to exercise their preexisting market power. The rapidly changing input costs during this period made it difficult for the customers to determine the reason and magnitude of the cost shocks. In such uncertain conditions, firms could also expect competitors to face the same disruptions and increase prices, thereby reducing the risk that a firm increasing its prices would be undercut. This not only justified their price increases but also gave them greater confidence that their rivals would follow.
Inflation spiked in the immediate aftermath of the Covid shock from 2021 to 2022. The subsequent decline in inflation in 2023-24 does not mean that the coordination broke down or market power disappeared. Conlon’s argument confuses inflation—the rate at which prices increase—with the price level itself. When companies set higher prices, they don’t have to keep increasing them at the same magnitude to maintain those ill-gotten margins. Disinflation does not necessarily mean that coordination failed; it could just be that the firms achieved a higher price equilibrium.
So many cartels
For the forgoing reasons, new cartel formation is not a necessary requirement for the profit-inflation hypothesis. But even if we credit Conlon’s (straw-man) requirement, there is substantial evidence of anticompetitive coordination in crucial economic markets during that specific time frame.
Consider RealPage. A complaint put forward by the Department of Justice (DOJ) and multiple states in 2024 alleges that competing property owners gave confidential details to RealPage about rental prices, lease conditions, and occupancy rates. RealPage incorporated this information into its pricing software and generated recommendations based partly on competing landlords’ data. The DOJ claimed that this method prevented property owners from reducing rents, offering fewer discounts and enabling them to set their prices together rather than competing separately for tenants.
Although RealPage was formed in 1998, the alleged conduct occurred right before and during the inflation surge. In February 2020, RealPage prepared to launch its AI Revenue Management platform, which relied on lease data covering 13.5 million units. The complaint further alleges that RealPage facilitated discussions among competing landlords about concessions in May 2020, pricing calculations in August 2020, and potential pricing adjustments in March and April 2021. The President’s Council of Economic Advisers analyzed and estimated that this algorithmic coordination increased rents in involved buildings by around $70 each month on average, or about 4 percent, making renters spend an estimated $3.8 billion. Given that housing represents over a third of the Consumer Price Index, and given the well-known rental price-fixing scheme, it is curious that Conlon never mentions RealPage.
Food markets give us another instance of an industry being cartelized and experiencing rapid inflation. In 2023, Agri Stats was sued by the DOJ for facilitating information sharing among big processors of chicken, pork and turkey. (Disclosure: Singer was an expert for a class of chicken growers and indirect pork purchasers in two Agri Stats matters. Both classes were certified, and the cases ended via settlements.) The lawsuit claims, during the period covering rampant inflation, that Agri Stats gathered confidential data about processing participants related to price, cost and production and distributed the detailed reports unavailable to buyers and public. Processors that subscribed to Agri Stats allegedly used the reports for setting prices and production levels. And Agri Stats would allegedly push processors at times to increase prices and limit supply. Even though its pork and turkey reporting was paused prior to the pandemic, the alleged information sharing persisted in the chicken sector throughout the inflationary period. Conlon never mentions the Agri Stat price-fixing litigation.
The frozen-potato litigation provides further evidence of price fixing in the food industry. The buyers claim that Lamb Weston, McCain Foods, J.R. Simplot and Cavendish Farms—processors that together dominate almost all of the market—planned a series of nearly simultaneous price hikes starting in 2021. These complaints, which were filed in 2024, point out several instances during this period where prices went up at the same time and assert that the cost for frozen potatoes increased by over 40 percent even though input costs were going down. Conlon never mentions the frozen-potato litigation.
Not to be upstaged, the beef industry provides an example of how preexisting concentration played out during the pandemic shock. Tyson, JBS, Cargill, and National Beef, the “Big Four,” controlled approximately 85 percent of beef processing. Lawsuits filed by ranchers, retailers, and distributors allege how these companies coordinated cattle purchases and slaughter volumes to restrict supply and depress the cattle prices, while it maintained higher beef prices. According to an investigation by the Food and Environment Reporting Network, when Covid outbreaks closed major Tyson and Cargill plants, the remaining processors allegedly reduced their cattle purchases rather than expanding production to capture their competitors’ sales. All four processors then raised their prices for the purchasers. During this period the wholesale price of choice beef cuts doubled while the price paid to cattle ranchers decreased by approximately 30 percent. Tyson and JBS have reached substantial settlements while denying any wrongdoing. These allegations illustrate precisely the mechanism that Conlon overlooks: a disruption can magnify the price effects of market power that existed before the shock began.
And these food cases are the ones covered in the mainstream business press. To document other price-fixing complaints in the food industry, we searched the news and analysis portion of Law360, a specialty law journal that tracks antitrust litigation, using keyword searches. Each search combined a food product name with a word like antitrust or price fixing. Next, we ran one structured search on Law360’s case database. We used the following filters: nature of suit set to Antitrust; industry set to Food-Major Diversified and Food Wholesale; and date range set from January 1, 2021, to July 24, 2026. The table below summarizes our results.
| Case Name | Case Number | District Court | Industry |
| United States of America et al. v. Cal-Maine Foods, Inc. et al. | 5:2026-cv-04060 | Northern Iowa | Eggs |
| In re: Nitrogen, Phosphorus, Potassium (NPK) Antitrust Litigation | 26-md-3187 | Kansas | Fertilizer |
| In re Frozen Potato Products Antitrust Litigation | 1:24-cv-11801 | Northern Illinois | Frozen Potatoes |
| US Foods, Inc. v. Agri Stats, Inc. et al | 1:26-cv-04459 | Northern Illinois | Broiler Chicken, Turkey, Pork |
| In re Granulated Sugar Antitrust Litigation | 0:24-md-03110 | Minnesota | Sugar |
| In re: Cattle and Beef Antitrust Litigation | 0:22-md-03031 | Minnesota | Cattle and beef |
| Conry, et al v. Gerber Products Company, et al | 1:24-cv-06784 (E.D.N.Y.), Judge Nina Gershon. A related, earlier filing exists in the Eastern District of Virginia (4/22/2024). | Eastern District of New York | Baby formula (infant formula) |
Our research found antitrust complaints alleging price-fixing in eggs, fertilizer, frozen potatoes, broiler chicken, turkey, pork, sugar, cattle and beef, and baby formula. In June 2026, the DOJ reached a settlement with the nation’s largest egg producers, which requires defendants to “end coordinated benchmark manipulation that artificially inflated prices across the country.” None of these cases were mentioned in Conlon’s paper. Consistent with the formation of these alleged food-related cartels, Conlon finds a large spike in the profit margins of consumer products in the second quarter of 2022 (Figure 7). He reports that “we see a drop in the margins of food manufacturers in 2024,” which is consistent with the pattern of food inflation (spiking in 2022 and falling in 2024).
To be fair, these cases do not prove that all food-related price hikes after the pandemic were due to explicit coordination. Yet they establish a point against Conlon’s thesis—namely, significant markers of anticompetitive coordination were present in important food markets during the time food prices were spiking. In the face of such evidence, it is odd that Conlon would conclude there wasn’t a “surge in newly organized cartels or widespread consolidation.”
An alternative hypothesis with zero evidence
Conlon is correct that citing higher total profits is not sufficient to distinguish between increased demand and reduced competition as the driver of inflation. Total profits can go up when companies sell more units above cost, make a larger profit margin on each item they sell, or both.
Conlon recognizes what kind of evidence would serve as the tie-breaker: “In the case of a demand shock, we would expect output to grow,” he writes, “while in the case of a change in conduct, we would expect output to fall.” Yet he fails to offer the very empirical analysis that his very framework requires. By his own calculations, he acknowledges that there was a notable rise in markups over costs (as opposed to total profits) that coincided with price spikes—which rules out the demand-driven explanation of more units sold—but does not resolve whether higher markups resulted from increased demand or increased coordination. Both treatments could dampen the demand elasticity, resulting in greater markups. Because empirical investigation of quantities is needed to disentangle the two dueling hypotheses, and because he offers none, Conlon has no basis upon which to invoke demand as the stronger candidate.
Conlon’s own analysis finds that market-wide markups, defined as the ratio of price to marginal costs, increased in 2020 and stayed high from 2021 until the third quarter of 2022, right as inflation began rising. In particular, he estimates that the total markup on a sales-weighted basis rose from about 1.60 in 2018 to around 1.66 by 2021, but then fell back to nearly 1.61 in 2023 (see Figure 8). This economy-wide trend is also observed in the food industry (see Figure 7), as food and consumer products enjoyed a spike in margins in 2022, before these margins returned to normal levels in 2023 and 2024. These correlations do not prove that higher markups caused inflation to rise. But they indicate that when markups went up, inflation increased; and when markups dropped back down, inflation decreased.
Finally, Conlon tests whether industries with greater markup growth between 2018 and 2024 experienced higher producer price inflation growth, finding no meaningful relationship as evidenced by a low R-squared. There are at least three problems with this test of the profit-inflation hypothesis. First, recall that proponents of this hypothesis believe that firms in concentrated industries exploited an economy-wide cost shock to raise prices by more than the true increase in costs. Hence, Conlon’s test omits a critical explanatory variable—namely, the cost shock brought about by Covid—which might bias his estimate on markup growth. It is the interaction of this cost shock with high levels of industry concentration that allegedly caused prices to spike. Second, when testing for a causal relationship of A (the treatment) on B (the outcome), the statistic of interest is not the R-squared but rather the estimated coefficient and standard error on the treatment (markup growth). Conlon (2026) never tells us whether that coefficient is economically or statistically significant or both. Going back and checking his 2023 paper, however, one learns that coefficient on markup growth is indeed positive and statistically significant at the one percent level. The objective of the model is not to maximize R-squared (or predict PPI growth in any given year); if that were the goal, one would add more explanatory variables. Rather, the goal is to isolate the impact of the treatment on the outcome variable, controlling for potential confounders. Conlon never tests that model. Third, even crediting the wrong statistic, the low R-squared in Conlon’s regression at the industry level cannot reject the hypothesis that firms were exploiting general cost increases in the economy, as opposed to cost increases in their own industries (the independent variable in Conlon’s univariate regression).
In summary, Conlon is right to suggest that accounting evidence alone is not enough to conclude the cause of inflation. But that limitation does not vindicate his preferred demand explanation either. Having identified output as the principal way to distinguish stronger demand from changed conduct, he never completes his own test. At best, his analysis demonstrates uncertainty about the cause of higher profits; it does not demonstrate that pricing coordination, whether tacit or explicit, among firms in concentrated industries played no causal role in the inflationary spike in 2021 and 2022.
It is the dream of many law professors to be cited in a judicial decision. It is not my dream to be cited, however, when the decision misunderstands the subject of my work, ignores other work, and ultimately comes to the wrong conclusion. That is what I’m reading in the court’s HPE-Juniper decision.
On August 12, Judge Pitts entered the proposed final judgment—the consent decree settlement between HPE-Juniper and the Department of Justice (DOJ)—finding the proposed final judgment to be in the public interest under the Tunney Act.
The court errs, in my opinion, in three fundamental ways: (1) It misunderstands what ought to be considered in the realm of public interest and what is not; (2) It misunderstands the role that evidence of corruption plays in terms of the “public interest;” and (3) It misunderstands that the whole point of the Tunney Act is that process matters.
As a brief backgrounder, the settlement occurred over the objections of Antitrust Division lawyers, including Roger Alford and William Rinner. Both were fired. A lobbyist for HPE, Mike Davis, reportedly threatened the head of the division, Abigail Slater: “If you don’t approve this settlement, I will destroy you. I will destroy your job at the DOJ.” Slater was forced out in February 2026. The concern among those in law enforcement and anti-monopoly community is that well-connected and powerful firms should not be able to buy their way around antitrust law, via patronage to the administration. This concern is particularly acute if the settlement permits an anticompetitive merger to be consummated.
On page 2 of the decision, the court explained the alleged infirmity in the states’ case to unwind the consent decree: “While the states have performed an invaluable public service in bringing to light additional details about the machinations at the DOJ that led to the settlement, they have not shown that entry of the amended proposed final judgment would not be in the public interest.” The court displays an interesting use of a double negative to avoid asking the more fundamental question: Is a consent decree in the public interest when it arose out of inappropriate contacts and political influence? The court answers yes, but only by committing two errors.
First, the court assumes that sunlight is the best disinfectant, and by bringing the information to light, the states have cured the harm. The notion that “sunlight is the best disinfectant” is embedded in notions of administrative law since Judge Louis Brandeis coined the term. But Brandeis’s full quote is “Sunlight is said to be the best of disinfectants; electric light the most efficient policeman.” That the states discovered the inappropriate contacts does not imply that those contacts carry no meaning in a public interest inquiry. That would be akin to saying that, although family of a defendant slipped the prosecutor a $100 bill, the plea bargain is still in the public interest. Process matters, and the process here, by the court’s own record, was badly flawed.
Moreover, given the way this administration has operated, it’s hard to claim that sunlight disinfects anything. Brandeis’s notion was that people would be outraged by misconduct. It is hard to muster sufficient sunlight to disinfect the firehose of corruption we current face.
Second, the court overlooked how procedural defects incentivize strategic dealmaking when crafting a settlement, pushing the needle towards the outer bounds of what is “the public interest.” The court states on page 28 that its “review of the amended proposed final judgment will therefore focus on whether the proposal is within the reaches of the public interest.” “Within the reaches of the public interest” suggests, however, that the proposed final judgement can be at the outer boundaries of the public interest, not squarely in it, and the court would accept the final judgment. Corruption, among other things, moves enforcement from what is squarely within the public interest to the outer territories.
And the reason that this settlement was on the outer boundaries of the public interest is because it was moved there by a tainted process. The court fails to recognize this problem, and instead doubles down by giving the DOJ deference:
The United States and HPE argue that the Court should grant significant deference to the United States’s decision to settle its lawsuit and its view of the public interest….The Executive Branch certainly has the prerogative to choose whether and how to prosecute any particular case. But the Executive does not have the authority under the Tunney Act to enter judicial orders with the binding force of law. Instead, both the Tunney Act and the nature of the parties’ request that the Court to exercise its own powers require that the Court exercise independent judgment about whether to do so. The Court will accordingly give the United States’s view of the public interest the deference appropriate to an experienced agency and to a party’s view of what actions best advance its interests.
I am not following this argument. It suggests that the DOJ gets deference even when there is a level of inappropriate contacts that raise questions.
Yet there is no requirement for judicial deference to an agency’s determination of the public interest in the Tunney Act. Indeed, the Tunney Act seeks to remove deference by elimination of judicial rubber stamping of consent decrees (the ultimate level of deference). It is striking indeed at a time when SCOTUS has eliminated levels of deference to administrative agencies (see Loper Bright) and has all but destroyed independent agencies (see Slaughter) that the court would come to the conclusion that an agency’s tainted, procedurally defective settlement deserves deference. Other commentators have noted the oddity of giving agency deference in the entry of a judicial decree: “a court’s entry of a consent decree is a judicial act which is both constitutional and statutory in nature. Thus, an intensive review of a consent decree by a district court may be supported apart from the Tunney Act.”
A missing citation
While I’m pleased that my Tunney Act article (one of them—more on this later) and others are mentioned in footnote 4 of the court’s decision, the court fails to note one important critic of deference—Congress. Per the Congressional Record, “As originally written, the Tunney Act serves two goals deterrence and mediation. The prospect of judicial scrutiny deters the Justice Department from heeding political pressure to enter a ‘sweetheart’ settlement.” And the legislative history of the Tunney Act amendment in 2004 also noted the possibility of moving the needle from the boundaries of public interest to something squarely within it:
And real Tunney Act review also provides an opportunity for a judge to act as a mediator, obtaining modifications to deficient settlements. As Professor Anderson points out, “[i]f the government and antitrust defendants come to perceive that meaningful [judicial] scrutiny is not a real threat, the door will be wide open for attempts to swing sweetheart deals and for the public to lose confidence in antitrust enforcement by the government.” 65 Antitrust Law Journal at 38.
The court failed to consider the larger ramifications of its entry of this decree, and the world is worse off for it.
Next, the court makes the remarkable conclusion that “The parties’ failure to comply with certain procedural requirements does not require rejection of the settlement.” The court notes that the parties failed to address the procedural requirements of the Tunney Act and then decides it is within the scope of its authority to enter the judgment anyway because the states discovered the omissions. And the omissions are troubling. First, “defendants failed to disclose, however, that Arthur Schwartz [a close confidante of Vice President JD Vance] had spoken on their behalf with DOJ officials Mizelle and Woodward, that Schwartz and Schultz [HPE’s Chief Operating and Legal Officer] had met with CIA Deputy Director Michael Ellis and Defense Under Secretary of Defense for Policy Elbridge Colby, and that Schultz had talked to the CIO of the National Security Agency and to individuals connected to the National Security Council.” Second, “although the Tunney Act required the United States to provide the public with a competitive impact statement that includes “a description and evaluation of alternatives to such proposal actually considered by the United States,” Id. § 16(b)(6), it did not disclose a complete list of alternative remedies it actually considered.”
The court puzzles as to what the remedy ought to be for such procedural defects but points out that because the states brought them to light, there is no harm. Under this standard, I look forward to robbing a department store while a sales rep discovers me so I might claim that, since the witness caught me, there is no injury. Such reasoning ignores the very real concern that this will be a signal that sweetheart deals are welcome, even if they are negotiated under questionable circumstances. This is not what the Tunny Act seeks as meaningful judicial review. The correct answer is the consent decree should have been rejected.
The wrong counterfactual
The court compares the outcome of the consent decree to a world in which the DOJ folds its tent upon failing to secure this settlement:
Given the risks that the United States would have faced at trial due to the relatively low market shares of HPE and Juniper, the fact that the proposed consent decree requires HPE to divest assets that others may be able to use to compete with HPE in the enterprise-grade WLAN solutions market, and the possibility that the United States could choose to walk away entirely from its challenge to the proposed acquisition if the settlement is not approved, entry of the proposed settlement serves the public interest.
Something isn’t better than nothing, and the Court mistakenly thinks its role is to compare the world in which DOJ abandons its challenge with the world in which it settles on the cheap. With that logic, even the most miniscule of consent decree would be considered in the public interest. That isn’t what the Tunney Act contemplates.
My coauthor on my first article on the Tunney Act, John J. Flynn, who was special counsel to the Senate Antitrust Subcommittee during the period when the Tunney Act was drafted and adopted and had a lot to do with drafting it, noted that the delineation of powers is clear. Prosecutorial discretion ends at the doors of judicial powers:
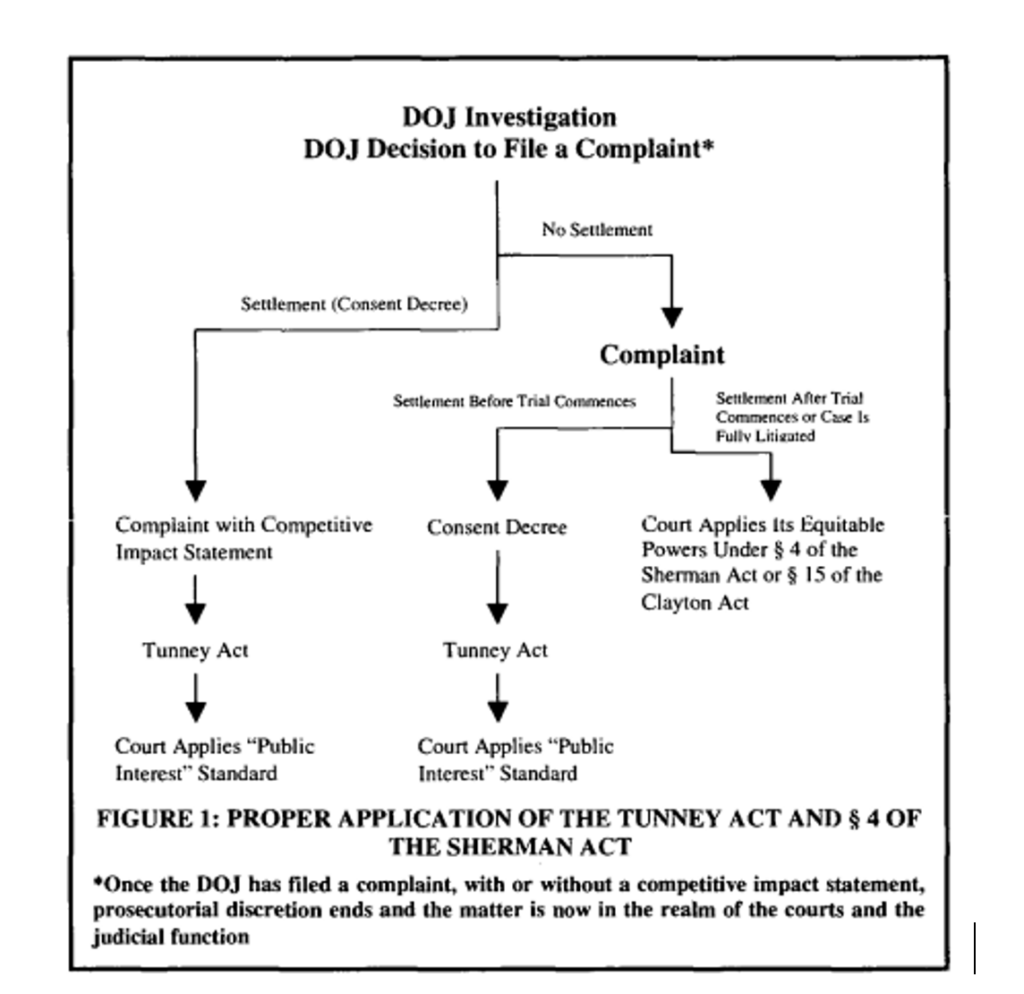
A court should not consider the DOJ’s prosecutorial discretion in its consideration of the public interest; to do so encroaches on judicial powers. It would be akin to a court accepting a plea bargain for the lightest sentence ever in a murder case because the prosecution could drop the case. The abdication of responsibility of the DOJ, in other words, is not one of the public interest considerations the court must ponder.
But it’s worse than that. As Lee Hepner points out (as does the Court):
HPE’s Schultz sent Woodward a draft competitive impact statement, writing, “We recognize that this document is typically prepared by the DOJ but thought we would share this draft in case it was at [all] useful to you.” … According to Rinner, aside from removing HPE’s commitment to maintain current prices, DOJ did not make any significant changes to the draft competitive impact statement HPE had provided. (citations omitted)
The court therefore implicitly gives DOJ deference for a proposal drafted by defendants and then claims that the settlement achieved by the DOJ is better than nothing.
It is not up to the states to fix DOJ’s errors, nor is it reasonable to expect them to continue to do so when the court uses it as a signal the proposed final judgment is in the public interest. Why waste time and resources in that manner?
The Tunney Act won’t save democracy
By focusing on the end result and overlooking the process, the court’s error is akin to watching a teenage driver run over multiple people and curbs but applauding the fact the car ultimately ended up in the driveway.
The court offers some consolation: “Even short of such an independent challenge, the states’ efforts may help inform the political process and future engagement with the Executive Branch in matters relating to antitrust enforcement.” How so? Congress spoke on the Tunney Act in 2004 and the Judiciary and the DOJ flat out ignored it. Also, the court must understand how fundamentally broken Congress is, so its platitude is somewhat baffling here.
I sadly predicted this outcome, when I wrote in August 2025 that the Tunney Act won’t save democracy:
The HPE-Juniper deal also raises serious questions related to the role of lobbying and whether the DOJ’s acquiescence has precious little to do with separation of powers and prosecutorial discretion and more to do with gangster antitrust. As the Wall Street Journal reported, “Hewlett Packard Enterprise made commitments, not disclosed in court papers, that called for the company to create new jobs at a facility in the U.S., according to people familiar with the matter.” This, if true, ought to be sufficient to reject the consent decree. But I doubt it. While SCOTUS is hard-core killing Chevron and administrative law, it seems totally fine with the extreme level of deference the DOJ gets under the bastardized interpretation of the Tunney Act.
There is potential to rehabilitate the Tunney Act. But not any time soon. And, as I’ve written before, while bills like the one Senator Klobuchar introduced as helpful, they are far from perfect. At the very least, Congress needs to define what is out of bounds for public interest determination (and what is within it). Prosecutorial abdication should not be one of the considerations. And there needs to be automatic rejection of consent decrees that are procedural defective.Finally, to Judge Pitts, many thanks for the citations! This is the article that, in my judgment, would have helped you the most. Alas, it was one you didn’t cite.
Local news in America has been dying for fifteen years, and national outlets are only barely doing better. Facebook and Google spent the 2010s and early 2020s absorbing the digital advertising revenue that used to fund local newsrooms. Ad dollars followed eyeballs because clickbait captures more attention than deeply researched long form writing, to platforms, and those platforms captured the value of news content—headlines, snippets, links driving engagement—without paying newsrooms anything close to what that content was worth to their own engagement metrics.
The result is well documented: newsroom employment cut by roughly half since 2008, more than two thousand local newspapers closed, and a genuine crisis of “news deserts“—counties with no local paper at all, tied by researchers to lower voter turnout, weaker government accountability, and even higher municipal borrowing costs. Meta’s own decisions to deprioritize news content in the Facebook feed, after years of encouraging publishers to build their distribution strategy around the platform, accelerated the collapse for outlets that had nowhere else to turn.
Generative AI is positioned to do the same thing to what’s left of the news business—only faster, and with less friction. The ad-platform extraction at least sent some traffic back to publishers: a reader clicking a Facebook link still landed on the newspaper’s site, saw its ads, sometimes converted to a subscription. A chatbot that synthesizes the news directly in the answer box closes that loop entirely. As explained on this site by Dilan Alma, there’s no click-through when the AI just tells you what happened. Search referral traffic to publishers has already begun measurably declining as AI-generated summaries answer queries directly in search results, and the mechanism is structurally identical to the one at issue in the copyright suits now working through the courts: the value of the reporting gets extracted into a product that competes with, rather than routes traffic to, the outlet that produced it.
A well-worn defense
AI defendants argue that requiring them to compensate newspapers and other creators for training content—and ruling against fair use—would put the United States behind China in AI development. Whatever one makes of that argument, licensing may add friction to AI development, and some of the damages sought by plaintiffs may prove excessive. But China does not have the independent local-news ecosystem that the United States does. If preserving American technological leadership requires accelerating the collapse of American journalism, we should at least acknowledge the tradeoff we are making. The United States could win the AI race and still lose something essential: an independent information system capable of holding American institutions accountable. The argument China will win if we make AI companies pay for inputs assumes that AI capability is the only strategic asset that matters. It isn’t.
This is why the copyright doctrine question in The New York Times Co. v. Microsoft Corp. and OpenAI, Inc. isn’t academic. Every time a court hands down a ruling in one of the AI training-data cases, someone reaches for Google LLC v. Oracle America, Inc. (2021) as the governing analogy. The instinct is understandable—it’s the most recent Supreme Court fair use decision involving a trillion-dollar tech platform, it involves code and interoperability, and Google won. For AI defendants, that combination is irresistible as a rhetorical shield. But the analogy doesn’t hold here, and if courts import Oracle’s outcome without its reasoning, the fair-use factor that’s actually built to ask “does this harm the market for the original” gets steamrolled before it can do its job—in a market that was already cut in half by the last extraction cycle. Local newsrooms, which operate on thinner margins and less brand loyalty than the Times, are the least equipped to survive a second wave of value extraction dressed up as fair use.
Following the precedent
Oracle sued Google over Android’s use of 37 Java API packages—specifically, the declaring code (the method headers and organizational structure programmers use to call pre-written functions) rather than the implementing code (the actual instructions that do the work). Google had written its own implementing code from scratch; what it reused was the API’s naming and organizational structure, because that structure was what millions of Java programmers already knew. The Supreme Court, in an opinion by Justice Breyer, assumed without deciding that the API declaring code was copyrightable, and held that Google’s use was nonetheless fair use as a matter of law.
Three things about the Court’s reasoning matter for the comparison to come:
First, the material copied was a system of interoperability, not expressive content. The Court repeatedly stressed that declaring code is “different” from other computer code because it’s bound up with uncopyrightable ideas and functional necessity—it’s the “method[] of operating” a system, closer to the buttons on a QWERTY keyboard than to a novel. Justice Breyer’s opinion draws directly on the merger doctrine and the idea/expression dichotomy: when there’s essentially one way to name a function that does a particular job in a way third-party programmers can use, the “expression” contained in that name is thin to the point of vanishing.
Second, the purpose of the copying was interoperability and reimplementation, not substitution. Google used the declaring code so that the millions of programmers who already knew Java could write for Android without relearning a new system. The Court treated this as “a new platform” that expanded—rather than substituted for—the market Oracle originally served with Java SE, which was desktop and enterprise computing, not mobile.
Third, and most important for what follows: the Court’s market-harm analysis found that Android did not act as a market substitute for the Java platform Oracle actually sold, and that Oracle in fact benefited from Java’s increased ubiquity even as it lost the Android licensing deal it wanted. The fourth fair use factor—the effect on the market for the copyrighted work—cut for Google because Sun/Oracle’s own licensing business model contemplated exactly this kind of platform-to-platform reuse, and the record did not show Android cannibalizing Java SE’s actual market.
Oracle v. Google, in short, is a case about (1) functional, non-expressive interoperability code, (2) reused for a new purpose, (3) in a market the copyright owner wasn’t actually competing in with the copied product. Not one of those conditions is satisfied in the news-copyright AI cases.
An entirely different animal
The New York Times v. Microsoft/OpenAI turns on a different kind of copying, for a different purpose, aimed at a market in which the plaintiff obviously does compete.
The material is thickly expressive, not functional. The Times’s complaint centers on millions of its articles—investigative reporting, essays, criticism, feature writing—ingested into training corpora and, the complaint alleges, capable of being reproduced by ChatGPT in outputs that are sometimes verbatim or near-verbatim. This is nothing like an API’s declaring code. There is no merger-doctrine argument that says there’s only one way to write a Times investigative feature; journalism is exactly the kind of expressive work around which copyright’s core protections were built. The functional/expressive line that did nearly all the work in Breyer’s opinion runs the opposite direction here.
The purpose is training a substitute product, not achieving interoperability with an existing standard. Google reused Java’s API structure so third parties could keep using skills they already had, on a new platform that did not replace the old one. OpenAI’s use of Times content, by contrast, trains a model that competes directly with the Times for the attention of readers seeking news and analysis—a chatbot that can summarize the day’s events, answer questions about them, and (per the complaint) sometimes reproduce the reporting itself, without the reader ever clicking through to the Times’s website. That is substitutional in exactly the way Android was found not to be. The Times doesn’t need OpenAI to reimplement its API to reach a new audience; OpenAI needs the Times’s reporting to make its product useful, and having gotten the benefit, routes attention away from the source rather than toward it.
The market-harm analysis also runs the other way. Oracle’s licensing business model contemplated derivative platform use; Sun had a history of encouraging just this kind of reuse before its litigation strategy changed. The Times’s business model is the diametric opposite: subscriptions and advertising, both of which depend on readers visiting the Times’s own product rather than getting the substance of its reporting mediated through a chatbot. If a generative AI tool can answer “What did the Times report about Trump’s press conference” accurately enough that the reader never needs to see the original, the fourth factor—market substitution—points toward infringement in a way it never could for Android and Java SE, because there was no evidence Android displaced Java SE licensing revenue, and there is very direct concern that AI summarization displaces subscription and pageview revenue for news publishers.
The scale and mechanism of copying also differ. Google reused a defined set of 37 API packages, disclosed and specific. Training-data cases involve ingestion of enormous, largely undisclosed corpora, often including outputs that can reproduce close paraphrases or verbatim excerpts of the underlying works—the “memorization” problem that has become a live discovery fight in nearly every one of these suits, including Bartz v. Anthropic and Thomson Reuters v. Ross Intelligence. That’s a different fact pattern than “we rewrote the implementation and kept your naming conventions.”
Put simply: Oracle v. Google is a case where the Court found thin/functional expression, transformative new-platform purpose, and no market substitution. The Times case, and most of the newsroom-plaintiff AI suits, present the opposite of all three. Citing Oracle as controlling authority in the news-copyright context is not applying precedent—it is borrowing the outcome of a case whose reasoning cuts against the party invoking it.
Shishene Jing is a Fellow at the Thurman Arnold Project at the Yale School of Management and a former antitrust attorney with the Federal Trade Commission Bureau of Competition Technology Enforcement Unit, where she worked on an investigation into the artificial intelligence industry. She clerked for Judge Jed S. Rakoff on the Southern District of New York and Chief Judge Robert A. Katzmann on the Second Circuit. She earned a JD from Yale Law School where she served as an Articles Editor on the Yale Law Journal and graduated with a B.A. in Economics from Stanford University. Her interests are in artificial intelligence, technology antitrust, labor antitrust, copyright, and regulation of creative industries.
In May, Zillow filed a lawsuit against real estate brokerage Compass Inc. and a large multiple listing services (MLS) firm in Chicago, claiming the two firms violated antitrust law by colluding to hide home listings from buyers. No matter the outcome in this dispute, the interests of American homebuyers and sellers likely will not be served, as the market has been effectively rigged.
To understand why, a brief history of real estate listings is in order. Two years ago, the National Association of Realtors (NAR) settled the Sitzer-Burnett class action and dropped the rule that forced listing brokers to publish a buyer-broker commission offer through the MLS. The 2024 NAR settlement was supposed to inject price competition into a market that had behaved, for decades, like a cartel. Buyer brokers would now have to negotiate their pay directly with buyers, exposing a commission pool of roughly $100 billion a year to ordinary market discipline. Zillow’s legal maneuvering against Compass and Midwest Real Estate Data LLC (MRED) is what you get when the platforms sitting on top of residential listings try to rebuild around the contours of the settlement instead of competing under it.
Start with Compass. A substantial share of its inventory now moves through “private exclusives” that circulate inside the Compass network first and reach the broader MLS only later, if at all. Sellers do not learn what an open market would have paid them. Buyers do not learn that competing inventory exists. Search costs rise on both sides, and the price-discovery function—what George Stigler called the whole point of intermediated markets—is degraded. The spread that opens up between what buyers pay and what sellers receive is where the platform takes its margin.
Turning to Zillow, the dominant online real estate and rental platform has built a more aggressive version of the same model. Zillow Preview launched in May with exclusive deals covering more than 60 of the largest brokerages in the country, including RE/MAX, Keller Williams, and HomeServices of America. A separate carriage agreement with Realtor.com gives the two platforms combined reach across roughly three-quarters of major portal visitors. Listings submitted through these deals appear only on Zillow and Trulia during an open-ended “Preview” period, and they may never reach an MLS or a competing site. Strip the pleadings away and Zillow’s lawsuit is one massive platform accusing the other of doing what both are actually doing now at scale.
Now look at how Zillow gets paid. When a buyer clicks “Contact Agent” or “Request a Tour” on a Zillow listing, they are not connected to the listing agent. Instead, they are routed to a buyer’s broker who pays Zillow up to 40 percent of the resulting commission. That 40 percent is not a competitive price for matching. It is economic rent, extracted from a buyer who does not know it is being extracted, and it lands precisely in the part of the transaction the NAR settlement was supposed to make competitive. Buyers overwhelmingly do not realize they are paying it. In a survey of more than 850 consumers, Wharton’s Jerry Wind found that fewer than one percent correctly identified who would be calling them after the click on Zillow’s website. Zillow Preview expands this extraction by capturing consumers earlier, before a listing ever reaches the MLS. Once inside the Zillow ecosystem, buyers face pressure toward Zillow Home Loans, which antitrust scholar Steven Salop has found to be significantly more expensive than market alternatives, with the steepest markups falling on veterans, low-income borrowers, and Black borrowers.
Economists recognize that when a critical input is foreclosed from rivals, anticompetitive effects can occur. Listings are the critical input here. Whoever controls them controls the buyer flow that monetizes through referral fees, mortgage cross-sells, and advertising. Network effects do the rest: brokerages list where the buyers are, buyers go where the listings are, and the platform’s take rate climbs without competitive constraint. Zillow’s own complaint conceded the point on its first page, calling listings “the most important information” in the market. That is a fair description of why the inventory is valuable. It is also a fair description of why Zillow and Compass are both racing to lock it up.
The welfare math is not abstract. Every percentage point of commission re-captured through referral fees, mortgage steering, or pre-market opacity is a percentage point of consumer savings the NAR settlement never delivers. The Wind survey on buyer routing and the Salop analysis on Zillow Home Loans are early evidence that the re-capture is already happening. And it is hitting hardest on the borrowers least equipped to detect it. That is what economic theory predicts when a platform with market power on one side of a transaction is allowed to lock up listings and tie in ancillary services.
And higher commissions are not the only anticompetitive effects. Third-party appraisal companies need access to all comparable home listings to make accurate valuations. If an appraisal company has access to the (public) MLS database but not to the other (private) set of potentially competing homes, the resulting appraisals could go haywire, leading to downstream frictions. For example, shoddy appraisals flowing from this information gap could give homeowners a false impression of their home’s value.
None of this requires policymakers to pick a winner in the Illinois fight. The real question is whether the platform layer of residential real estate, having watched the NAR settlement weaken its single largest source of opaque pricing power, is now being allowed to rebuild that power through exclusive listing deals, hidden referral fees, and tying arrangements with adjacent services. On the evidence so far, the answer looks like yes. The cost falls on consumers who never had a seat at either company’s table.
The Law and Economics (L&E) movement is coming under critical scrutiny these days. And deservedly so. It has spawned opposition schools of thought, including the emerging Law and Polical Economy (LPE) movement. In a recent post on LPE Blog, Madison Condon and Luke Herrine suggest that L&E approaches “mostly derive from the neoclassical tradition.” We write only as a caution to not throw out all of mainstream economics, as not all of mainstream economics supports L&E policies.
As a friendly modification, we suggest as a finer point: Neoclassical economics consists of both a scientific aspect and an ideological aspect, and it is only the latter from which L&E derives its foundations.
By ideology, we mean mainstream theories that are known to be inconsistent, based on unrealistic assumptions, or empirically false, but that remain a prominent part of economic textbooks and economic education. They are what Paul Krugman refers to a “zombie economics” in his book “Arguing with Zombies: Economics, Politics, and the Fight for a Better Future.” Zombie economic theories survive despite their known deficiencies in the profession.
While consistent evidence-based economic theories can have political implications, it is noteworthy that all of the neoclassical zombie economic theories justify policy that benefit the powerful groups in our society. Krugman mentions, for example, austerity theories (advocating cutting spending in a recession), “free trade benefits all,” and “tax cuts increase growth” as examples of widely held economic views reflected in most textbooks that do not survive serious scrutiny.
What is the ideology that undergirds L&E? Professors teaching L&E to students often begin by explaining that the core themes of the movement are that (1) the common law is efficient, and (2) the proper goal of the law is efficiency. But what is efficiency? This is the heart of L&E ideology. To begin with, it may come as a surprise given its rhetoric that no economist has ever proven that a real-world market economy is efficient. Typically, economists cite to the proof by Arrow and Debreu for this proposition. What Arrow and Debreu actually proved was that under extreme assumptions—firms acting as if they were infinitely small, all agents having perfect information including about the future (or perfect information about the probabilities), costless entry, and all goods being homogeneous (meaning no brands or special features), an equilibrium point will exist where supply equals demand.
Many such points can exist, however, and there is no proof that an economy would ever reach such a point even given the extreme assumptions. As Joeseph Stiglitz explains in his recent book “The Road to Freedom: Economics and the Good Society,” Arrow and his colleagues believed that they had proven that a market economy is not necessarily efficient because of the strong assumptions necessary to get the existence result. But later economists came to use the result as ideology, as support for the efficiency of markets.
A problematic efficiency standard
The first theorem of welfare economics establishes that the equilibrium points of an Arrow-Debreu economy are Pareto Efficient. This means that at that point no one could be made better off without making someone else worse off. Essentially, a policy move is Pareto efficient only if everyone impacted agrees; that is, the policy gets unanimous consent. But in any real economy, economic theory can say almost nothing about the benefits or costs of a market economy. Nonetheless, there is no shortage of economists that claim that a market economy leads to efficiency.
Graduate students in economics learn that “efficiency” means Pareto Efficiency. But this is not the definition of efficiency used by L&E. If we consistently adopt this definition, then economists have nothing to offer regarding legal policy. If no one is harmed, and at least one person claims he/she is better off, this allocation must be an improvement in welfare. Few policy decisions let alone litigation outcomes ever involve zero losers.
The definition of efficiency behind L&E is not Pareto Efficiency. It is the Kaldor-Hicks measure of efficiency, also called the Potential Pareto Efficiency standard. The idea is that a policy is an improvement or an increase in efficiency if all the losers could potentially be compensated, even if they are not compensated. For example, if output is higher, then there is a Potential Pareto improvement, irrespective of the impact on distribution. As we show in our paper, every L&E textbook has adopted this definition of efficiency. This is another Zombie ideological economic concept. We say this because the entire economic subfield of welfare economics (those economists that study welfare and measures of efficiency) have rejected Potential Pareto efficiency as hopelessly flawed and ethically untenable.
Among other problems, welfare economists showed that output or value can be measured by willingness to pay or willingness to accept. Both are equivalently valid measures. These two measures can differ, however, leading to serious inconsistencies. In 1950, Gorman showed that the assumption needed to prevent these inconsistencies (many but not all of them) is that people buy the same products, in the same amounts, when their income changes. For example, if you eat one pizza a week when you make $10,000, if you make $100,000, you must still eat one pizza a week. A completely absurd assumption. Economists rarely discuss these assumptions, even though they are made explicit in graduate textbooks where they are buried in difficult mathematics.
A second serious problem is that to treat everyone’s willingness to pay as equal amounts of welfare, we have to assume that society should consider that an additional dollar has the same value for a rich person as a poor person. Otherwise welfare depends on distribution and Potential Pareto is not a valid measure of welfare, and therefore can’t be a useful measure of efficiency. The vast majority of people would hold this assumption (this value judgment) to be false. Nonetheless, L&E is premised on Kaldor-Hicks efficiency, an approach rejected by welfare economists, but kept alive as ideology in economics.
The equity-efficiency “tradeoff”
In our paper “The Core Value of Public Policy Should be Equality,” we show that numerous social scientists (includingeconomists) have demonstrated that equality, i.e. equity in distribution, has an enormous positive impact on human well-being. So how can L&E use a theory that by definition eliminates distribution from the discussion of efficiency? They must employ a third economic ideological myth: the equity-efficiency “tradeoff.” That notion is that there is a social tradeoff between how equal income is an economy and the economy’s rate of growth. Equality is supposed to dilute incentives for work and hence to slow down growth. One can find this idea of a tradeoff in many basic economic textbooks. But again, this idea is a zombie, it has no basis, it survives because of the ideological power of the idea. To see this, take, for example, the experience of the United States. The graph below is from Piketty’s work on economic equality.
As the above figure shows, the period of the 1950s through the1970s is far more equal than the period from the 1990s to the present. So what are the growth rates? Turns out that the average growth rate of the first period was 3.9% and the second period was 2.6%
To further test the underlying premise for the notion that there is an equity-efficiency tradeoff, here is a simple scatter plot of data taken in three-year non-overlapping periods beginning with 1947–1949 and ending with 2022–2024 (which is the most recent data available) for “annual growth rate of real disposable income per capita” in the United States, versus the average U.S. Gini coefficient for income.
Figure 1: Gini Coefficient source is: https://www.census.gov/data/tables/time-series/demo/income-poverty/historical-income-families.html. Economic data from U.S. Bureau of Economic Analysis, Real Disposable Personal Income: Per Capita [A229RX0A048NBEA], retrieved from FRED, Federal Reserve Bank of St. Louis; https://fred.stlouisfed.org/series/A229RX0A048NBEA, January 28, 2026
Even without doing any statistical analysis, it is plain to see that the purported tradeoff between equality and efficiency is unsupported. Greater inequality (i.e., higher Gini coefficients as one moves to the right) has been associated with a lower growth rate. The data are clearly divided into two eras, an earlier one with low inequality and high growth (the top-left quadrant), and a more recent one with high inequality and low growth (the bottom-right quadrant), with 1986–1991, the end of the Reagan Administration and most of the George H.W. Bush Administration, being the transition period. The same is true across countries. As we show in our paper on equality, virtually all the economic studies show that more equal countries grow faster than unequal countries. Our conclusion is that the equity-efficiency tradeoff is another example of mainstream economic ideology.
The potential role for LPE legal scholars in understanding contemporary social problems is enormous, while the assumptions of L&E limits its ability to understand these issues. The great increase in economic inequality, which is a critical factor in human welfare, is not explained by market forces, but instead by changes in the legal framework in which the economy operates. As the legal realists demonstrated long ago, there is no such thing as a “free” market. All markets are embedded in legal structures that influence their outcomes. For example, few contracts would ever be signed if the state took no role in contract enforcement.
For another example, where output is produced by corporations, the legal relationships between the shareholders, managers, and other stakeholders influence potential and actual corporate decisions, and these stakeholder relationships are governed by corporate law. The role of finance is determined by securities law and financial regulations. The influence of workers is affected in important ways by labor law. In addition, the market is embedded in an entire superstructure that is strongly influenced by numerous other laws, regulations, and norms. These conditions are instrumental to how income is distributed. Bernard Harcourt adopts a similar point of view in his book “The Illusion of Free Markets: Punishment and the Myth of Natural Order,” although he does not address the period we are analyzing here.
Mark Glick is Professor of Public Policy and Adjunct Professor of Law at the University of Utah; Gabriel Lozada is Professor of Economics at the University of Utah; Darren Bush is the Leonard B. Rosenberg Professor of Law at the University of Houston.